• Skip to main content
  • Skip to primary sidebar
  • Skip to footer

Windsor Wealth Management LLC

Investment service in Topsfield, Massachusetts

  • Home
  • About
    • Disclosure
  • Our Difference
  • Services & Fees
    • When to Hire a Financial Advisor
    • FAQ’s
  • Blog
  • Retirement Checklist
  • Contact

Windsor Insights

Market Update: Good News & Some Caution Signs

October 21, 2026 by David Bunker Leave a Comment

[Quick Reminder: Open enrollment is approaching! See our post 5 Financial Tasks to Tackle Before Fall for helpful tips on reviewing your benefits and more.]

There’s plenty to cover when it comes to the economy and markets.

Most of the news is good, but there are some concerns worth keeping an eye on.

So let’s break down what’s going on, including:

  • Stock Market & Corporate Earnings: Are stocks getting too expensive?
  • Jobs & Unemployment: Hiring is slowing, but unemployment remains low.
  • Consumer Spending: Why are consumers spending when they’re so pessimistic?
  • Economy & Inflation: Growth remains strong, but inflation is still a concern.
  • Risks We’re Watching: Higher energy prices and interest rates.
Image Source: ChatGPT

Stock Market

The stock market is up roughly 14% year-to-date (with dividends).

However, as the November midterm elections approach, we’ll likely see more volatility.

But consider this:

The market has delivered positive returns in the 12 months following every single midterm election since 1946.


Corporate Earnings

Corporate earnings are strong, with some sectors rising roughly 15% to 25% from a year ago. (Some analysts anticipate 30% or more growth by year-end.)

Driving this growth is the significant spending on AI and data centers, benefiting tech companies and other businesses supporting the buildout.

Interestingly, with such high earnings and a strong stock market, some investors worry stocks are becoming too expensive.

But this isn’t necessarily the case.

Keep in mind, stock prices are only part of the equation; what companies earn also matters.

Here’s a simple example:

Say a company’s stock price goes up 10%, but its earnings go up 25%.

Yes, the stock costs more, but the company is also earning significantly more.

Because earnings grew faster than the stock price, the stock can actually be less expensive relative to what the company earns.

That’s why a rising stock market doesn’t necessarily mean stocks are becoming more expensive.


Jobs & Unemployment

The unemployment rate was 4.20% in September, up slightly from 4.10% in August.

It’s still low by historical standards.

In general, if someone wants a job, they can typically find one. (See YCharts’ summary of monthly unemployment rates dating back to August 2022.)1

Also, job growth has slowed.

There were 133,000 jobs added in August, and only 29,000 in September.

Overall, employers are still hiring, but cautiously.


Consumers Are Spending, But Pessimistic

Consumer sentiment is hovering near low levels: 46.3 in October vs. 56.4 in January, according to University of Michigan survey data.2

Yet, consumer spending continues to trend upward.

This sounds contradictory, but think about your own household.

You may not like paying more for groceries or gas, but you’re likely still buying groceries, filling the tank, going out to dinner and taking the occasional trip.

Also, wages are rising slightly faster than inflation.

Overall, consumers may not feel particularly good about the economy, but their behavior tells a different story.


The Economy Is Growing

The broader economy continues to do well.

The Atlanta Fed’s GDPNow model estimates that the economy grew at a 3.6% annualized rate in the third quarter.3

GDPNow is a running estimate that’s updated as new economic reports become available, including data on consumer spending, business investment, housing, trade and the labor market. The estimates often change rapidly when new reports come out.


Inflation: The Fed Raised Rates in September

Inflation is running at about 3.8%, above the Fed’s 2% target.

To help bring inflation down, the Fed recently raised short-term interest rates by a quarter of a percentage point.

Higher interest rates make borrowing more expensive, which can slow spending and ease inflation.

The Fed’s goal isn’t to lower prices, but to slow how quickly they rise.

The challenge is bringing inflation down without slowing the economy too much.


Two Risks We’re Watching

Risk #1—Energy Prices

Energy prices are a key risk right now.

Oil has jumped to around $91 a barrel, up from $70 before the Iran conflict.

This matters since nearly everything we buy travels by truck at some point.

When diesel prices rise, transportation costs increase, and these added expenses can eventually show up in the prices we pay for everything from groceries to household essentials.

Risk #2—10-Year Treasury Yield

We’re keeping a close eye on longer-term interest rates, particularly the 10-year Treasury yield. It’s up quite a bit (currently about 5.24%) compared to 4.18% in late 2025.

Higher Treasury yields can increase borrowing costs, including mortgage and auto loan rates.

They can also make relatively safe investments (e.g., Treasury bonds) more attractive than stocks, putting downward pressure on stock prices and potentially leading to lower portfolio returns.

Finally, rising Treasury yields can cause existing bond prices to fall, potentially reducing the value of your bond holdings.

To help manage this risk, we use a strategy called bond laddering. Rather than investing in bonds that all mature at the same time, we spread their maturity dates over several years.

For example, as shorter-term bonds mature, we can reinvest the proceeds in new bonds, potentially taking advantage of higher interest rates.

Deep Dive Resource: Fidelity explains how to build a bond ladder in their article, How to earn steady income with bonds.4

As always, please reach out with any questions.

Dave


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Sources:

1: YCharts, US Unemployment Rate, https://ycharts.com/indicators/us_unemployment_rate

2: YCharts, US Index of Consumer Sentiment, https://ycharts.com/indicators/us_consumer_sentiment_index

3: Federal Reserve Bank of Atlanta, Current and Past GDPNow Commentaries, https://www.atlantafed.org/research-and-data/data/gdpnow/current-and-past-gdpnow-commentaries

4: Fidelity.com, How to earn steady income with bonds, https://www.fidelity.com/viewpoints/investing-ideas/bond-ladder-strategy
Filed Under: Economy, Financial Planning, Inflation, Stock Market, Windsor Insights

2 Social Security Myths Worth a Closer Look

September 25, 2026 by David Bunker

Earlier this month, we talked about Social Security’s funding challenge and what Congress can do about it.

Today, let’s talk about some misconceptions.

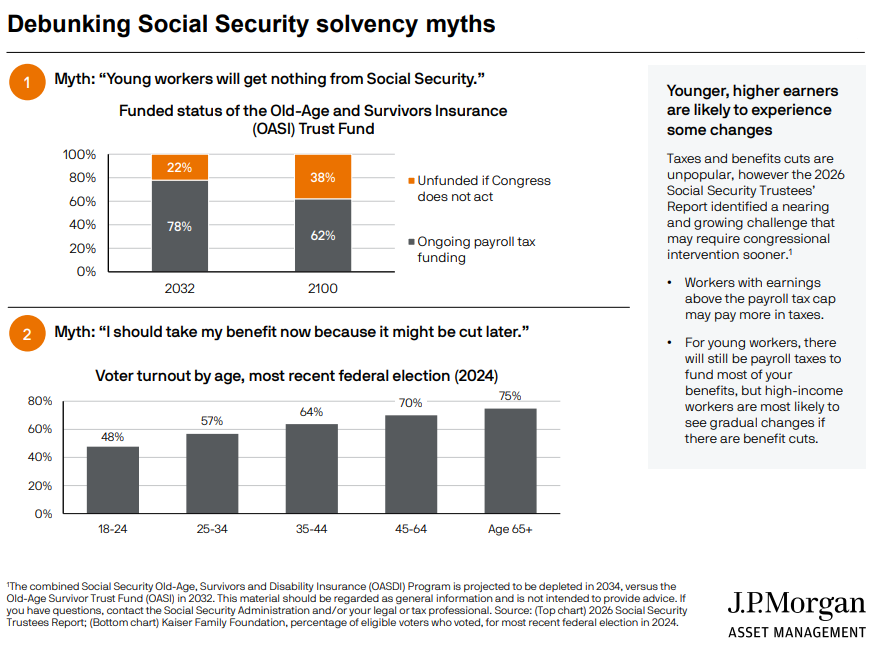
This J.P. Morgan chart helps put these into perspective:


Chart Source: J.P. Morgan Asset Management, 2026 Guide to Retirement1

Myth #1—Young workers will get nothing from Social Security.

Not quite.

As you can see in the chart, even under a worst-case scenario where Congress does nothing, ongoing payroll taxes will still cover 62% of promised benefits through 2100.

Social Security isn’t going away, but future payout formulas will likely change.

Given this potential gap, building personal savings early is critical for younger generations.

As a courtesy to you, we’re happy to meet with your adult children to help them navigate workplace retirement plans, investing and other financial decisions. If someone in your family could use a sounding board, feel free to introduce us.


Myth #2—I should take my benefit now because it might be cut later.

While understandable, concern over potential policy changes is only one factor in your claiming decision.

A big reason sudden benefit cuts for current retirees are unlikely comes down to political reality: older Americans consistently vote at the highest rates.

As the voter turnout chart highlights, 75% of adults aged 65 and older turned out in the 2024 federal election, compared to just 48% of 18-to-24-year-olds.

Because this group carries so much voting power, lawmakers face immense pressure to protect current retirees. Future adjustments, therefore, are likely to be phased in gradually over time or target higher earners rather than impact current benefits.


Bottom Line

Social Security faces real challenges, but uncertainty doesn’t have to drive your financial decisions.

Whether you’re encouraging younger family members to save early or deciding when to claim your own benefits, focus on what you can control: saving, planning ahead and making decisions based on your individual circumstances.

As always, please reach out with any questions.

Dave


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.

Source:

1: J.P. Morgan Asset Management, Guide to Retirement, https://cdn.jpmorganfunds.com/content/dam/jpm-am-aem/global/en/insights/retirement-insights/guide-to-retirement-us.pdf


Filed Under: Financial Planning, Social Security, Windsor Insights Tagged With: Social Security

Should you worry about Social Security?

September 15, 2026 by David Bunker

It feels like every few months another headline warns that Social Security is running out of money.

In reality, Congress has several options to keep the program funded.

So, let’s look beyond the headlines at what’s actually happening, and what can be done about it.


A Confident Retirement Starts With Understanding Your Options
(Image Source: Gemini AI)

Where the Money Comes From

Before we look at legal levers, let’s clear up how Social Security actually works…

Overall, it’s designed to be self-funding: you and your employer each contribute 6.2% of your wages to Social Security, and benefits are paid from the Social Security Trust Funds. (Social Security has two funds.)1

In the past, there were many more workers than retirees, creating surplus cash that was set aside in the trust funds.

Today, Social Security takes in less than it pays out in benefits, so it’s drawing on its trust fund reserves to make up the difference.

So when people say, “Social Security is becoming insolvent,” what this actually means is that the “extra” savings are getting low, leaving primarily payroll taxes to cover benefits.

Keep in mind, in the 1950s there were roughly 16.5 workers paying into the system for every Social Security beneficiary. Today, there are only about 2.6 workers per beneficiary.2

Also, not everyone pays into the system. Many state employees, teachers and others rely on separate government pensions instead of Social Security.


Fixing the Funding Gap

Congress has several policy levers it can pull before benefits are impacted by a funding shortfall.

These aren’t recommendations, but examples of the options Congress could consider, including:

Raising or Removing the Wage Limit: Right now, Social Security taxes only apply to earnings up to $184,500 (for 2026). Raising or removing this cap would mean Social Security taxes apply to more income, bringing in additional revenue.

Increasing the Payroll Tax: Gradually raising the tax rate by just a fraction of a percentage point across the workforce would create a steady stream of new funding.

Using Other Tax Revenues: Additional funds could come from outside payroll taxes, e.g., corporate taxes or capital gains.

Adjusting the Retirement Age: Pushing the full retirement age (FRA) to 68 or 69 for younger workers gives the program time to adjust, without touching benefits for anyone currently retired.

Rebalancing Benefit Growth: Keep full, promised benefit growth for lower-wage workers while slightly slowing how quickly benefits grow for higher-income brackets.

Modifying Cost-of-Living Adjustments (COLAs): Adjust how annual cost-of-living increases are calculated to reflect how people actually shop when prices increase.

For Example:

Standard inflation calculations using the Consumer Price Index (CPI) assume a retiree keeps buying expensive beef even if prices jump 15%.

An updated formula (Chained CPI) recognizes that people adjust by buying cheaper options, e.g., chicken, which results in a lower inflation rate, enabling slightly smaller annual benefit increases.


Bottom Line

Social Security does face a funding challenge, but “running out of money” doesn’t mean benefits suddenly disappear—despite what some headlines suggest.

Instead, there are many options to bring more money into the system and reduce future costs.

The challenge is deciding which changes to make.

In the meantime, we can plan around what we know and prepare for what may change.

We also address two common Social Security misconceptions here: 2 Social Security Myths Worth a Closer Look.


[Resource]: Social Security is just one piece of the retirement income puzzle. For another perspective on making your retirement savings last, read our post: 3 Steps to Help Your Money Outlive —You


If you have any questions, please reach out.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Sources:

1: SSA.gov, What are the Trust Funds?, https://www.ssa.gov/news/en/press/what-are-the-trust-funds.html

2: SSA.gov, Covered Workers and Beneficiaries, https://www.ssa.gov/oact/TR/2026/lr4b4.html


Filed Under: Financial Planning, Retirement Planning, Windsor Insights Tagged With: Social Security

8 Important Ages in Retirement Planning

August 31, 2026 by David Bunker

It’s hard to believe summer’s almost over.

As the season shifts, it’s important to review your upcoming milestones.

To help you keep track, here’s a quick reference highlighting eight key ages that can trigger important retirement planning opportunities and decisions.


Retirement rules, however, are rarely as simple as reaching a specific age.

Therefore, keep these nuances in mind:

Age 50: Catch-up contributions begin in the calendar year you turn 50. For 2026, the 401(k) catch-up limit is $8,000, increasing to $11,250 for ages 60–63 in 401(k) and other workplace retirement plans.1

[Resource]: See our 2026 Key Financial Data guide for more details regarding contribution limits, Social Security benefits, Medicare premiums, tax rates and more.

Age 59½: The 10% early-withdrawal penalty generally goes away at this age, but that doesn’t make every withdrawal tax-free. For example, Roth IRA earnings are only tax-free once you’re 59½ and have satisfied the 5-year rule from your first Roth contribution.

[Resource]: Read Fidelity’s guide to Roth IRA withdrawal rules for a breakdown of early distributions, penalty exceptions and inherited account requirements.2

Age 62: You can begin Social Security retirement benefits, but claiming before your full retirement age (FRA) permanently reduces your monthly benefit by as much as 30%. Also, if you continue working while receiving benefits before your FRA, the Social Security earnings test may temporarily reduce your benefits.3

Age 65: This is generally when Medicare eligibility begins. However, if you or your spouse are still working and have qualifying employer health coverage, you may be able to delay Medicare enrollment without penalty. Different rules apply depending on your coverage.

Age 67: Once you reach full retirement age, you’re eligible for 100% of your Social Security benefits. Also, the earnings test ends, so extra earned income won’t reduce your benefits.

Age 70: Delaying Social Security beyond your FRA can increase your monthly benefit, but there’s no additional benefit for waiting past age 70.

Age 70½: You can donate tax-free directly from an IRA to a charity via a Qualified Charitable Distribution (QCD).

[Important]: Once Required Minimum Distributions (RMDs) begin, make your QCD before taking your taxable distribution because a QCD can’t retroactively offset a distribution you’ve already taken.

Age 73: Under the SECURE 2.0 Act, the RMD age increased from 72 to 73 starting in 2023. The law also established a second increase, raising the RMD start age to 75 beginning in 2033.

Note: Because RMDs can push you into a higher tax bracket later in life, the years leading up to age 73 create an ideal window to consider tax planning strategies in your 50s and 60s, such as Roth conversions.

Tracking these milestones is important, but turning them into a proactive plan is where the real value lies.

If you have questions, please reach out.

Enjoy the rest of your summer!

Dave

P.S. In case you missed it, we recently published a new blog post: 5 Financial Tasks to Tackle Before Fall


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


Sources:

1: IRS, Retirement Topics-Catch-up Contributions, https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-catch-up-contributions

2: Fidelity.com, Roth IRA withdrawal rules, https://www.fidelity.com/learning-center/trading-investing/roth-ira-withdrawal-rules

3: SSA.gov, What happens if I work and get Social Security retirement benefits?, https://www.ssa.gov/faqs/en/questions/KA-01921.html

Filed Under: Financial Planning, Retirement Planning, Windsor Insights

5 Financial Tasks to Tackle Before Fall

August 19, 2026 by David Bunker

As summer winds down, it’s a good time to take a few minutes to review your finances before the busy fall season begins.

Here are five areas worth checking now.

Image Source: ChatGPT

#1—Plan for Age 18

If your child or grandchild is turning 18 or heading off to college, make sure they have the legal documents that allow you to help them if there’s a medical emergency.

Overall, it’s a good idea to have:

  • HIPAA Authorization
  • Medical Power of Attorney
  • Living Will
  • Durable Power of Attorney

Related Post: Turning Age 18 Legalities & Grandchild College Planning

Also, if your student is living on or off campus, consider whether renter’s insurance makes sense. Replacing specialized computer equipment can be costly. The same goes for e-bikes, which many students use to get around campus and can cost thousands to replace.

Note: While your homeowners policy may cover some losses in a dorm, e-bikes and high-value tech often require special endorsements or separate policies.

Finally, if you’re using a 529 plan, coordinate your withdrawals carefully. Using the same education expenses for both a 529 withdrawal and an education tax credit can lead to unexpected tax consequences.

Fidelity does a nice job explaining it here: How to spend from a 529 college plan1


#2—Get Ready for Open Enrollment (Medicare & Employer)

Open enrollment season is just around the corner.

Medicare’s Annual Enrollment Period runs from October 15—December 7, and many employers hold open enrollment in the fall.

Before finalizing your benefits, consider the following:

Health Insurance Coverage: Compare plan costs, deductibles, provider networks and out-of-pocket maximums to determine whether your current plan is still the best fit.

Prescription Drug Coverage: Make sure your medications are still covered and compare costs if your prescriptions or health needs have changed.

Health Savings Account (HSA) Contributions: If you’re eligible for an HSA, review your contribution amount during open enrollment. HSAs offer triple tax advantages, including tax-deductible contributions, tax-deferred growth and tax-free withdrawals for qualified medical expenses.

Flexible Spending Accounts (FSAs): Estimate next year’s eligible healthcare or dependent care expenses so you can elect an appropriate contribution amount.

Life and Disability Insurance: Review your coverage after major life events (e.g., birth, divorce or marriage). If your employer allows you to increase coverage without a medical exam during open enrollment, consider whether additional protection makes sense before your health changes.

Retirement Plan Contributions: Increase your contribution rate if you’re receiving a raise or bonus. Also, make sure you’re contributing enough to receive your full employer match.

Are you turning age 65 soon?

Your Medicare initial enrollment timeline is different from the annual enrollment period.

Most people can enroll in Medicare beginning three months before the month you turn 65 and continuing for three months afterward.

However, if you’re still covered by an employer health plan, different rules may apply.

Give us a call before you enroll, so we can help you sort through your options.

[Resource]: For a timeline of critical milestones—including RMD start dates and Social Security thresholds—see our guide: 8 Important Ages in Retirement Planning.

[Resource]: Here’s our detailed Medicare guide describing initial enrollment timelines, premiums and deductibles for 2026.


#3—Review Your Taxes and Retirement Savings

Now is a great time to see whether you’re on track.

Review your paycheck withholdings to help avoid an unexpected tax bill or an unnecessarily large refund next spring. Also, check your retirement plan contributions to see if you’re on pace to maximize your 401(k), 403(b), etc. before year-end.

Keep in mind, if you’re age 50 or older and make catch-up contributions, be aware that recent law changes may require higher earners to make catch-up contributions on a Roth (after-tax) basis.


#4—Update Your Homeowners Insurance

Have you remodeled your kitchen, finished a basement or added a garage?

Major home improvements can increase the cost to rebuild your home. If you’ve completed significant renovations, review your homeowners insurance to help ensure your coverage keeps pace with your home’s current value.

Also, if you’ve added a pool, consider adding an umbrella policy.


#5—Plan Ahead for Holiday Spending

It may feel early, but the holiday shopping season will be here before you know it.

Therefore, take a few minutes now to decide how much you want to spend on gifts, travel and entertaining.

Setting a budget early can help reduce financial stress and prevent overspending later in the year.


If you have any questions, please reach out.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.

Source:

1) Fidelity.com, How to spend from a 529 college plan, https://www.fidelity.com/learning-center/personal-finance/college-planning/college-529-spending

Filed Under: College Planning, Estate Planning, Financial Planning, Financial Planning, Taxes, Windsor Insights

Longevity Risk: What if you live longer than expected?

July 28, 2026 by David Bunker

When people think about retirement risk, market downturns usually come to mind first.

But there’s another risk that deserves just as much attention: living a long life.

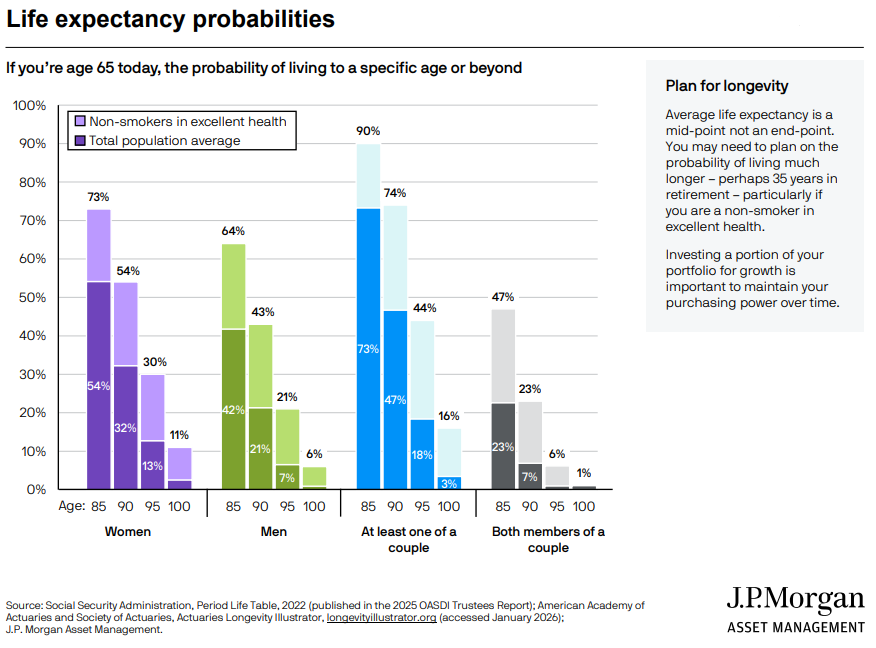
Life expectancy is often thought of in terms of averages (e.g., age 85 for women). But averages can be misleading when you’re planning for retirement.

Consider the chart below.

If you’re 65 today, there’s a 74% chance at least one member of a healthy couple will reach age 90, and a 44% chance one will live to 95.

In reality, the odds of a long retirement are higher than many people realize.


Chart Source: J.P. Morgan Guide to Retirement1

RELATED: We touched upon spouse protection planning in a recent post, and why planning for a surviving spouse becomes increasingly important when retirement may last decades.


Long Retirements

A retirement that lasts 30+ years can place very different demands on your financial portfolio than one lasting 15 or 20 years.

As retirement stretches into decades, carefully managing your investment strategy, withdrawal rate, Social Security timing, taxes, healthcare costs and inflation can help your savings last longer.

Overall, equities play an important role as the long-term growth engine of an investment portfolio, and we believe they help mitigate the longevity risk most people face.


Curious how long you might need your retirement plan to last?

Here are three longevity calculators that provide different perspectives:

Living To 100: A comprehensive questionnaire (40 questions) based on longevity research that considers health, family history and lifestyle.2

Blue Zones® True Vitality Test: Estimates longevity based on the lifestyle habits common among the world’s longest-living populations.3

Social Security Life Expectancy Calculator: A quick government estimate based on your date of birth and gender.4

Of course, no calculator can predict exactly how long you’ll live. However, they can help put longevity risk into perspective.

If you have any questions, please reach out.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Sources:

1) J.P. Morgan Guide to Retirement, https://cdn.jpmorganfunds.com/content/dam/jpm-am-aem/global/en/insights/retirement-insights/guide-to-retirement-us.pdf

2) Living To 100, Scientific Life Expectancy Calculator, https://www.livingto100.com/

3) Blue Zones® True Vitality Test, https://apps.bluezones.com/en/vitality

4) Social Security, Life Expectancy Calculator, https://www.ssa.gov/oact/population/longevity.html


Filed Under: Retirement Planning, Windsor Insights Tagged With: Longevity Risk

Tax Planning During Your 50s & 60s

July 15, 2026 by David Bunker

There are certain moments in life when tax planning becomes especially important. If you’re in your 50s or 60s, this is one of them.

Retirement isn’t simply the end of a career; it’s a transition to a new way of generating income.

While many people spend decades building their retirement savings, fewer spend time planning how to withdraw the assets tax-efficiently.

Image Source: ChatGPT

This is important because:

  • Your tax return may look very different in retirement.
  • Your sources of income begin to change.
  • You may have years when you’re temporarily in a lower tax bracket.

These changes can create valuable financial planning opportunities.

Here are three key retirement tax planning opportunities, followed by a short roundup of other areas to optimize.


#1—Roth Conversions

A Roth conversion allows you to move money from a traditional IRA into a Roth IRA.

You pay income taxes on the amount you convert today, but qualified withdrawals from the Roth IRA are tax-free in the future.

Key benefits include:

  • Creating a source of tax-free retirement income, enabling greater flexibility when managing withdrawals.
  • Filling up a lower tax bracket. (Converting just enough money to maximize today’s low tax rate without pushing yourself into a higher one.)
  • Paying taxes now to reduce taxes later.

[Resource]: For a timeline of critical milestones—including RMD start dates and Social Security thresholds—see our guide: 8 Important Ages in Retirement Planning.

Also, a Roth conversion typically creates a more tax-efficient inheritance for your heirs.

You pay the taxes today, allowing your beneficiaries to receive tax-free withdrawals from an inherited Roth IRA, assuming the Roth rules are met. By comparison, withdrawals from an inherited traditional IRA or 401(k) are generally taxable as ordinary income.1

Roth conversions need to be modeled extensively, since they can increase your modified adjusted gross income. We use two software tools for Roth conversion planning, including Holistiplan and Income Lab.

Reach out if you’d like to model some scenarios.

Keep in mind, Roth conversions can often take years to reach a breakeven point.


#2—Social Security Claiming Timing

Many people think the Social Security decision comes down to one question: Should I claim early or wait?

This is important.

However, the timing of your benefits can also impact your tax strategy.

For Example:

Imagine you retire at age 64 but don’t plan to claim Social Security until age 70.

During these six years, you may have little taxable income because you’ve stopped working, haven’t started receiving Social Security and Required Minimum Distributions (RMDs) haven’t begun.

These lower-income years may create opportunities to:

  • Complete Roth conversions while you’re in a lower tax bracket.
  • Withdraw money from tax-deferred retirement accounts at lower tax rates.
  • Reposition investments before additional retirement income begins.

The key isn’t simply deciding when to claim Social Security. It’s coordinating the decision with the rest of your retirement income plan.


#3—Tax Diversification & Tax–Efficient Withdrawals

A well-diversified portfolio can help manage investment risk, while a tax-diversified portfolio can increase flexibility when it’s time to generate retirement income.

Ideally, your retirement savings are spread across three tax buckets:

  • Taxable (brokerage accounts)
  • Tax-deferred (traditional IRAs and 401(k)s)
  • Tax-free (Roth IRAs and 401(k)s)

Having assets in each of these buckets gives you more choices when generating retirement income. Instead of withdrawing from the same account every year, you can select the accounts that best fit your tax situation.

For Example:

If you realize a large capital gain (e.g., selling an investment property or appreciated investments) you may choose to rely more on tax-free Roth IRA withdrawals for this particular year rather than taking additional taxable distributions from a traditional IRA.

Over time, this flexibility may help make your retirement income strategy more tax efficient.

Related Post: Stress-Free Retirement Spending: The Investment Bucket Strategy

While Roth conversions, Social Security and tax buckets form the foundation of a solid plan, a truly tax-efficient retirement requires watching the fine print, too.


More Opportunities for Lifetime Tax Savings

Finding meaningful savings comes from looking at the whole picture and making small, coordinated moves over time.

Here are nine additional tax-planning opportunities we monitor with you to help minimize your lifetime tax liability:

Medicare IRMAA Surcharges: Manage your income levels to avoid triggering higher Medicare Part B and Part D premiums. Before recognizing a large gain or completing a Roth conversion, look at whether it could push you into a higher IRMAA bracket. Here’s our chart reflecting Medicare Parts B and D income-related adjustments.

Related Post: Medicare: The $1 Mistake that Costs $3,500.

Capital Gains Planning: Review your portfolio for opportunities to strategically harvest tax losses or realize gains to offset future liabilities.

Estate Planning & Lifetime Gifting: Consider whether it makes sense to transfer assets to children or grandchildren now to complement your broader estate and tax plan.

Stock Options & Concentrated Stock: Develop a multi-year plan for diversifying single-stock positions to manage investment risk and tax challenges.

Health Savings Accounts (HSAs): Continue funding your HSA if eligible, since it’s one of the most tax-efficient ways to save for future healthcare expenses.

Catch-Up Contributions: Maximize available catch-up contributions if you’re age 50 or older, and strategically split them between traditional and Roth accounts when applicable. See our chart for contribution limits.

Charitable Giving: Utilize Qualified Charitable Distributions (QCDs) or donate appreciated securities instead of cash to maximize the tax efficiency of your giving.

Required Minimum Distributions (RMDs): Plan ahead for future mandatory distributions well before they begin to help reduce their impact on your ordinary income.

Spouse Protection Planning: Anticipate the transition from a joint to a single tax return, which can increase tax obligations (widow’s tax) since a survivor no longer has the larger joint deduction. Maximizing Social Security to secure a higher survivor benefit, combined with early Roth conversions to reduce future taxable distributions, can help protect a surviving partner’s income down the road.

RESOURCE: Fidelity has written an excellent article explaining 4 Retirement Tax Surprises, including shifting tax brackets, surcharges, the widow’s penalty and fewer deductions.2

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Sources:

1) IRS.gov, Retirement topics-beneficiary, https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-beneficiary

2) Fidelity.com, 4 retirement tax surprises, https://www.fidelity.com/learning-center/wealth-management-insights/avoid-tax-surprises-in-retirement


Bay Colony Advisors, DBA Windsor Wealth Management, is not a Certified Public Accountant and does not provide tax, legal, or accounting advice. Any tax-related information provided is for general informational purposes only and should not be construed as legal or tax advice. Each individual’s tax situation is unique, and you should consult with your own tax, financial, or legal advisors before making any decisions. We strongly recommend seeking the advice of a qualified CPA or other professional for personalized tax advice.


Filed Under: Financial Planning, Retirement Planning, Taxes, Windsor Insights

Quick Tax Check Before the Year Gets Away

June 29, 2026 by David Bunker

Earlier this month, we looked at how major life events (e.g., death, new job or retirement) impact your financial plan.

But sometimes, the most valuable planning opportunities don’t wait for a major milestone.

Instead, they build up quietly in your day-to-day tax situation.

An unexpected bonus or shifting into a new tax bracket can quietly alter your financial landscape. To help ensure you aren’t leaving money on the table, we built a quick Mid-Year Tax Checkup for you below.

Take 60 seconds to scan the checklist and see which items apply to you:

Click here to view or print a full-size version of the checklist.

If several items apply to you or if you’re unsure how they impact your situation, please reach out.

The second half of the year is a great time to make adjustments.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Bay Colony Advisors, DBA Windsor Wealth Management, is not a Certified Public Accountant and does not provide tax, legal, or accounting advice. Any tax-related information provided is for general informational purposes only and should not be construed as legal or tax advice. Each individual’s tax situation is unique, and you should consult with your own tax, financial, or legal advisors before making any decisions. We strongly recommend seeking the advice of a qualified CPA or other professional for personalized tax advice.


Filed Under: Financial Planning, Income, Retirement Planning, Taxes, Windsor Insights, Windsor Money Minute

  • Page 1
  • Page 2
  • Page 3
  • Interim pages omitted …
  • Page 9
  • Go to Next Page »

Primary Sidebar

Search Our Blog

Past Insights

3 Steps To Help Your Money Outlive—You

Market Update: Good News & Some Caution Signs

2 Social Security Myths Worth a Closer Look

Should you worry about Social Security?

8 Important Ages in Retirement Planning

5 Financial Tasks to Tackle Before Fall

Longevity Risk: What if you live longer than expected?

Tax Planning During Your 50s & 60s

Quick Tax Check Before the Year Gets Away

Market Highs & Mid-Year Review (5 key items)

Instead of Retiring, Many Are Doing This (4 Alternatives)

3 Key Portfolio Maneuvers & New Market Highs

Your Retirement Budget vs Inflation; Protecting Purchasing Power

The Guest Who Never Leaves (and wasn’t invited)

Markets Don’t Send Invitations When the Best Days Arrive

Investing Perspectives Regarding the Middle East Conflict

The 3-Year “Buffer Strategy” for Portfolios

How to Make the Decision to Retire

Medicare: The $1 Mistake that Costs $3,500

2026 Tax Planning Resources & Key Financial Data

A Key Trend Worth Watching & Your Portfolio

Rate Cuts, Jobs, Growth: A Look at 2026

Happy Thanksgiving + Power of Gratitude, Explained

Today’s Economy: What’s Actually Going On?

3 Later-in-Life Conversations; Important Decisions as Life Changes

5 Financial Moves to Make Before Year-End

The Fed Cuts Rates, Here’s Why It Matters

September 2025 Market Update & Key Trends

Stress-Free Retirement Spending: The “Bucket” Strategy

Today’s New Reality: Spotting Scams

2025 Tax Changes: One Big Beautiful Bill Act (OBBBA)

Clear Thinking: Are You Defining the Right Problem?

AI Is Booming, Diversification Matters

Mid-Year Review: Small life changes can have big financial impacts

Top 2025 Summer Travel Spots & Average Costs

Planning Your Final Days of Work Before Retiring

Is market news scaring you? Here’s the bigger picture.

Home Energy Audits and Energy Tax Credits

How To Spend Confidently & Without Regret in Retirement

Our Response to Recent Market Volatility

S&P 500 Shifts From Home Runs to Singles and Doubles

Footer

Amplify Your Retirement Income

"Prolonging Retirement Income" Checklist
Please enable JavaScript in your browser to complete this form.
Name *
Loading

Windsor Insights

Market Update: Good News & Some Caution Signs

[Quick Reminder: Open enrollment is approaching! See our post 5 Financial Tasks to Tackle Before Fall for helpful tips on reviewing your benefits and … [Read More...] about Market Update: Good News & Some Caution Signs

More Posts from this Category

  • Home
  • About
  • Testimonials
  • Contact

Windsor Wealth Management, LLC · 27 Main Street · Topsfield, MA 01983 · (978)887-6940 · WindsorWM.com · Email Us

Investment Advisory Services offered through Bay Colony Advisors, an SEC Registered Investment Advisor

Disclosure
Form ADV Part 2A – Disclosure Brochure
Form ADV Part 3: Relationship Summary Bay Colony Advisory Group, Inc.

Copyright © 2026 · Website Design · Admin

Copy written by financial services writer Sharron Senter