• Skip to main content
  • Skip to footer

Windsor Wealth Management LLC

Investment service in Topsfield, Massachusetts

  • Home
  • About
    • Disclosure
  • Our Difference
  • Services & Fees
    • When to Hire a Financial Advisor
    • FAQ’s
  • Blog
  • Retirement Checklist
  • Contact

Financial Planning

Should you worry about Social Security?

September 15, 2026 by David Bunker

It feels like every few months another headline warns that Social Security is running out of money.

In reality, Congress has several options to keep the program funded.

So, let’s look beyond the headlines at what’s actually happening, and what can be done about it.

A Confident Retirement Starts With Understanding Your Options
(Image Source: Gemini AI)

Where the Money Comes From

Before we look at legal levers, let’s clear up how Social Security actually works…

Overall, it’s designed to be self-funding: you and your employer each contribute 6.2% of your wages to Social Security, and benefits are paid from the Social Security Trust Funds. (Social Security has two funds.)1

In the past, there were many more workers than retirees, creating surplus cash that was set aside in the trust funds.

Today, Social Security takes in less than it pays out in benefits, so it’s drawing on its trust fund reserves to make up the difference.

So when people say, “Social Security is becoming insolvent,” what this actually means is that the “extra” savings are getting low, leaving primarily payroll taxes to cover benefits.

Keep in mind, in the 1950s there were roughly 16.5 workers paying into the system for every Social Security beneficiary. Today, there are only about 2.6 workers per beneficiary.2

Also, not everyone pays into the system. Many state employees, teachers and others rely on separate government pensions instead of Social Security.


Fixing the Funding Gap

Congress has several policy levers it can pull before benefits are impacted by a funding shortfall.

These aren’t recommendations, but examples of the options Congress could consider, including:

Raising or Removing the Wage Limit: Right now, Social Security taxes only apply to earnings up to $184,500 (for 2026). Raising or removing this cap would mean Social Security taxes apply to more income, bringing in additional revenue.

Increasing the Payroll Tax: Gradually raising the tax rate by just a fraction of a percentage point across the workforce would create a steady stream of new funding.

Using Other Tax Revenues: Additional funds could come from outside payroll taxes, e.g., corporate taxes or capital gains.

Adjusting the Retirement Age: Pushing the full retirement age (FRA) to 68 or 69 for younger workers gives the program time to adjust, without touching benefits for anyone currently retired.

Rebalancing Benefit Growth: Keep full, promised benefit growth for lower-wage workers while slightly slowing how quickly benefits grow for higher-income brackets.

Modifying Cost-of-Living Adjustments (COLAs): Adjust how annual cost-of-living increases are calculated to reflect how people actually shop when prices increase.

For Example:

Standard inflation calculations using the Consumer Price Index (CPI) assume a retiree keeps buying expensive beef even if prices jump 15%.

An updated formula (Chained CPI) recognizes that people adjust by buying cheaper options, e.g., chicken, which results in a lower inflation rate, enabling slightly smaller annual benefit increases.


Bottom Line

Social Security does face a funding challenge, but “running out of money” doesn’t mean benefits suddenly disappear—despite what some headlines suggest.

Instead, there are many options to bring more money into the system and reduce future costs.

The challenge is deciding which changes to make.

In the meantime, we can plan around what we know and prepare for what may change.

We also address two common Social Security misconceptions here: 2 Social Security Myths Worth a Closer Look.


[Resource]: Social Security is just one piece of the retirement income puzzle. For another perspective on making your retirement savings last, read our post: 3 Steps to Help Your Money Outlive —You


If you have any questions, please reach out.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Sources:

1: SSA.gov, What are the Trust Funds?, https://www.ssa.gov/news/en/press/what-are-the-trust-funds.html

2: SSA.gov, Covered Workers and Beneficiaries, https://www.ssa.gov/oact/TR/2026/lr4b4.html


Filed Under: Financial Planning, Retirement Planning, Windsor Insights Tagged With: Social Security

5 Financial Tasks to Tackle Before Fall

August 19, 2026 by David Bunker

As summer winds down, it’s a good time to take a few minutes to review your finances before the busy fall season begins.

Here are five areas worth checking now.

Image Source: ChatGPT

#1—Plan for Age 18

If your child or grandchild is turning 18 or heading off to college, make sure they have the legal documents that allow you to help them if there’s a medical emergency.

Overall, it’s a good idea to have:

  • HIPAA Authorization
  • Medical Power of Attorney
  • Living Will
  • Durable Power of Attorney

Related Post: Turning Age 18 Legalities & Grandchild College Planning

Also, if your student is living on or off campus, consider whether renter’s insurance makes sense. Replacing specialized computer equipment can be costly. The same goes for e-bikes, which many students use to get around campus and can cost thousands to replace.

Note: While your homeowners policy may cover some losses in a dorm, e-bikes and high-value tech often require special endorsements or separate policies.

Finally, if you’re using a 529 plan, coordinate your withdrawals carefully. Using the same education expenses for both a 529 withdrawal and an education tax credit can lead to unexpected tax consequences.

Fidelity does a nice job explaining it here: How to spend from a 529 college plan1


#2—Get Ready for Open Enrollment (Medicare & Employer)

Open enrollment season is just around the corner.

Medicare’s Annual Enrollment Period runs from October 15—December 7, and many employers hold open enrollment in the fall.

Before finalizing your benefits, consider the following:

Health Insurance Coverage: Compare plan costs, deductibles, provider networks and out-of-pocket maximums to determine whether your current plan is still the best fit.

Prescription Drug Coverage: Make sure your medications are still covered and compare costs if your prescriptions or health needs have changed.

Health Savings Account (HSA) Contributions: If you’re eligible for an HSA, review your contribution amount during open enrollment. HSAs offer triple tax advantages, including tax-deductible contributions, tax-deferred growth and tax-free withdrawals for qualified medical expenses.

Flexible Spending Accounts (FSAs): Estimate next year’s eligible healthcare or dependent care expenses so you can elect an appropriate contribution amount.

Life and Disability Insurance: Review your coverage after major life events (e.g., birth, divorce or marriage). If your employer allows you to increase coverage without a medical exam during open enrollment, consider whether additional protection makes sense before your health changes.

Retirement Plan Contributions: Increase your contribution rate if you’re receiving a raise or bonus. Also, make sure you’re contributing enough to receive your full employer match.

Are you turning age 65 soon?

Your Medicare initial enrollment timeline is different from the annual enrollment period.

Most people can enroll in Medicare beginning three months before the month you turn 65 and continuing for three months afterward.

However, if you’re still covered by an employer health plan, different rules may apply.

Give us a call before you enroll, so we can help you sort through your options.

[Resource]: For a timeline of critical milestones—including RMD start dates and Social Security thresholds—see our guide: 8 Important Ages in Retirement Planning.

[Resource]: Here’s our detailed Medicare guide describing initial enrollment timelines, premiums and deductibles for 2026.


#3—Review Your Taxes and Retirement Savings

Now is a great time to see whether you’re on track.

Review your paycheck withholdings to help avoid an unexpected tax bill or an unnecessarily large refund next spring. Also, check your retirement plan contributions to see if you’re on pace to maximize your 401(k), 403(b), etc. before year-end.

Keep in mind, if you’re age 50 or older and make catch-up contributions, be aware that recent law changes may require higher earners to make catch-up contributions on a Roth (after-tax) basis.


#4—Update Your Homeowners Insurance

Have you remodeled your kitchen, finished a basement or added a garage?

Major home improvements can increase the cost to rebuild your home. If you’ve completed significant renovations, review your homeowners insurance to help ensure your coverage keeps pace with your home’s current value.

Also, if you’ve added a pool, consider adding an umbrella policy.


#5—Plan Ahead for Holiday Spending

It may feel early, but the holiday shopping season will be here before you know it.

Therefore, take a few minutes now to decide how much you want to spend on gifts, travel and entertaining.

Setting a budget early can help reduce financial stress and prevent overspending later in the year.


If you have any questions, please reach out.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.

Source:

1) Fidelity.com, How to spend from a 529 college plan, https://www.fidelity.com/learning-center/personal-finance/college-planning/college-529-spending

Filed Under: College Planning, Estate Planning, Financial Planning, Financial Planning, Taxes, Windsor Insights

Instead of Retiring, Many Are Doing This (4 Alternatives)

May 27, 2026 by David Bunker

Retirement is changing.

For years, the traditional idea was simple: pick a date, stop working, and move fully into retirement.

But today, many people are taking a different path.

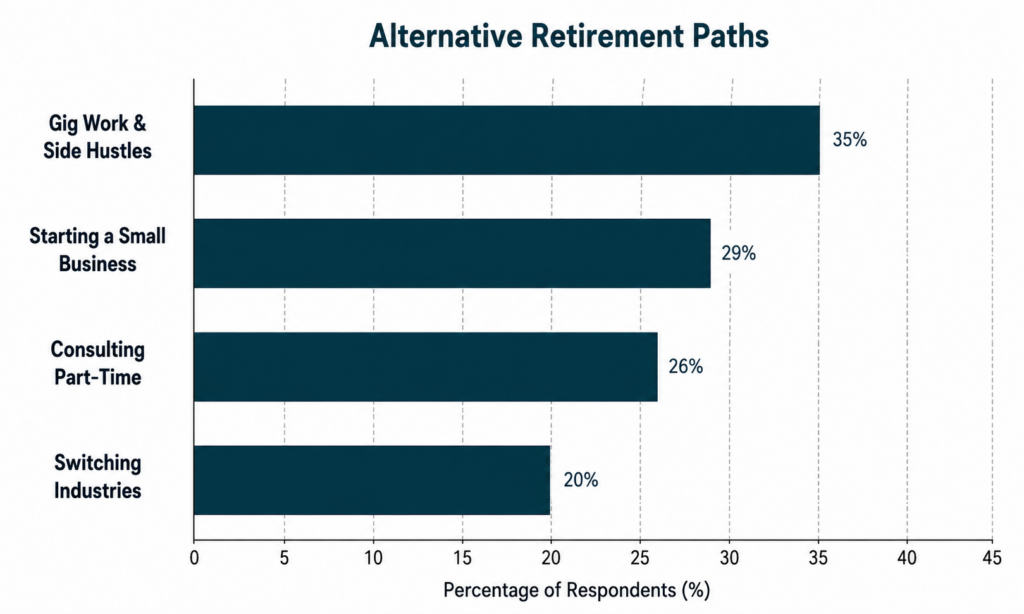
According to a recent Fidelity study, 61% of respondents are moving away from the “hard stop” approach and instead transitioning into retirement gradually.1

While many choose to simply scale back hours at their current jobs, this chart highlights four other ways people are approaching retirement:


Chart Data Source: Fidelity


Among all study respondents, the top retirement transitioning alternatives include gig work and side hustles (35%), starting a small business (29%), consulting part-time (26%), or switching industries altogether (20%).


Retirement Isn’t Just a Date on the Calendar

For many people, retirement is becoming more of a transition than a single decision. This often requires thoughtful planning across both personal and financial areas, including:

  • Defining Your Purpose: Determine exactly how much daily structure, flexibility, intellectual stimulation, optional income and engagement you need.
  • Optimizing Income & Flexibility: Even modest part-time income can reduce portfolio withdrawals while creating more flexibility around taxes and portfolio growth.
  • Controlling Portfolio Withdrawal Timing: An adaptable transition can help protect your portfolio from sequence-of-returns risk, minimizing the need to sell assets during market downturns.
  • Reducing Anxiety: A phased transition allows you to ease into retirement gradually instead of feeling pressured into a sudden life change.

Overall, retirement is a series of choices, not a single decision.

We explore how to navigate this process and what the “4 Phases of Retirement” look like in our post: How to Make the Decision to Retire

Keep in mind, there’s no “right” way to retire.

However, if it’s top-of-mind for you, reach out as soon as possible. The earlier we plan, the more financial flexibility you’ll likely have.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Source:

1) Fidelity Investments® Study, https://newsroom.fidelity.com/pressreleases/fidelity-investments–study–72–of-americans-say-they-will-retire-on-their-own-terms-as-they-embrac/s/609fbcb7-3ea5-4773-a300-0659da881d2a


Filed Under: Financial Planning, Retirement Planning, Windsor Insights

Your Retirement Budget vs Inflation; Protecting Purchasing Power

April 28, 2026 by David Bunker

In client meetings, we often hear:

“If I have $180,000 a year in retirement, I’m set.”

It’s a great goal.

On paper, it sounds reasonable. But the problem with “magic numbers” is they’re static targets in a moving world.

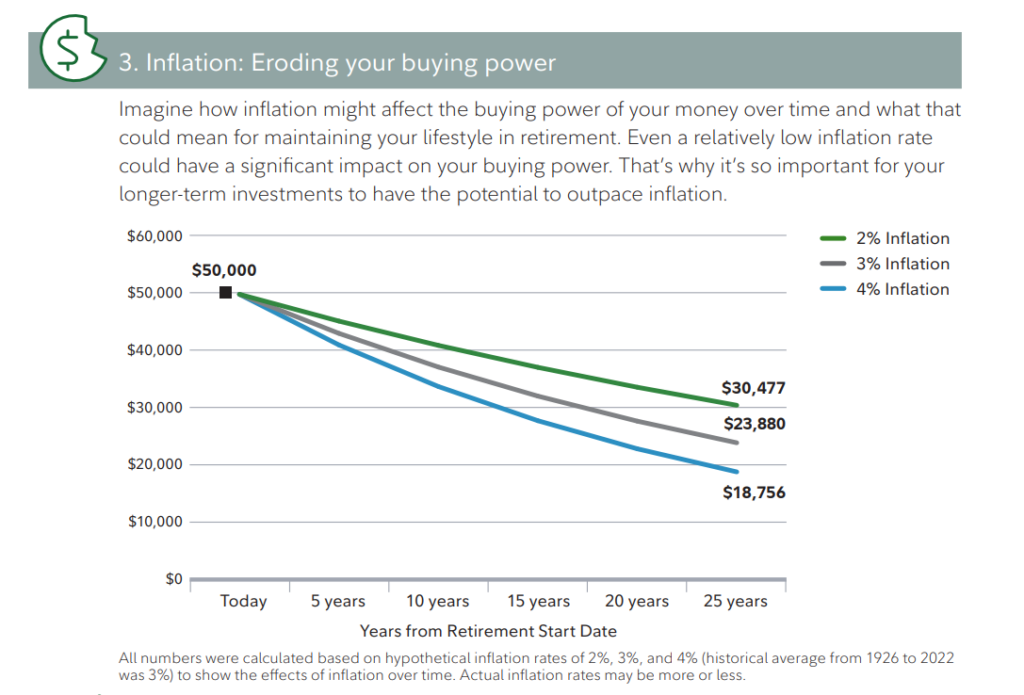
Fast forward 25 years, and that same $180,000 may only feel like $100,000.

Not because your portfolio failed, but because inflation quietly changed the math.

This Fidelity chart highlights the erosion. Even a modest 3% inflation rate can cut purchasing power in half over a typical retirement span:


Chart Source: Fidelity1

Inflation compounds over time. And by the time you feel it, your money doesn’t go as far as it used to.

So what do we actually do about it?

For your portfolio, we don’t treat inflation as an afterthought.

We plan for it from the start.


POSITIONING FOR GROWTH

We allocate a portion of your portfolio to assets that have historically outpaced inflation.

In practice, this means focusing on:

  • Pricing Power: Investing in companies that can pass rising costs on to consumers, protecting your profit margins.
  • Growing Income: Prioritizing dividend-paying companies with track records of increasing payouts to help your cash flow keep pace with rising prices.
  • Asset Location: Strategically placing your growth investments in the most tax-efficient accounts, helping to ensure more of your gains remain available for your future spending.

Another Thought

Inflation is just one of the “Big Five” challenges we manage within your retirement strategy.

To see how inflation interacts with the other four (longevity, healthcare, volatility and withdrawals), take a look at this Fidelity breakdown of the Big Five Retirement Risks.

–David Bunker, Financial Advisor & Licensed Fiduciary

P.S. If you’d like to see how inflation and the national debt tie together, read our post: The Guest Who Never Leaves (and wasn’t invited)


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Source:

1) Fidelity, Retirement Income Planning, https://www.fidelity.com/bin-public/060_www_fidelity_com/documents/income-diversification.pdf


Filed Under: Financial Planning, Inflation, Investments, Windsor Insights Tagged With: Inflation

The Guest Who Never Leaves (and wasn’t invited)

April 17, 2026 by David Bunker

Let’s kick off April with a riddle:

I’m the guest who never leaves, yet I’m never on the invite list.

I grow while you sleep, I eat before you sit down to dinner, and I’m currently worth about $114,000 for every person in America. Most people ignore me because I’m “too big” to understand—until I start quietly nibbling away at your retirement savings.


The guest’s name? The National Debt.

The total is nearly $39 trillion. It’s a massive, unsettling number.

What’s more, a debt of this magnitude forces the government’s hand, leading to the “quiet” erosion of your purchasing power.

Our role is to help manage these side effects over time.


Three Debt-Control Levers

To manage debt, the government typically pulls three levers. Each move helps stabilize the national balance sheet, but typically creates a “hidden tax” on your savings.

The levers include:

  • Allowing Inflation to Climb: One way to pay off debt is by letting the dollar’s value shrink. By weakening the dollar’s power, the government essentially pays back its obligations with “cheaper” money. While this lightens the debt load, it means you face higher costs in your daily life.
  • Letting Interest Rates Fluctuate: Currently, about 75% of U.S. debt is owned domestically. With the government selling more debt each year, it must raise interest rates to entice buyers to move from “I have enough” to “I’ll take more.” In general, every dollar spent on debt interest is a dollar diverted from public services and infrastructure.
  • Raising Taxes: When inflation and interest rate adjustments aren’t enough to cover the gap, tax policy becomes the final lever. This is the most direct way the government bridges the deficit, often resulting in higher tax rates or fewer deductions.

Your Portfolio: Controlling the Controllables

The debt total is mostly out of our hands.

However, we can control our response to it.

Our approach focuses on insulating your portfolio from the downside risks.

This starts with how we position your assets for the long haul using four key strategies:

#1—Protecting Your Buying Power

Inflation doesn’t happen all at once; it’s a slow erosion of your lifestyle.

To counter this, we rely on growth assets like equities diversified across both U.S. and international companies.

The goal is to help ensure your money keeps pace with rising costs so your standard of living never has to shrink to fit the economy.

#2—Getting Ahead of Future Taxes

If your money is mostly in tax-deferred accounts like traditional IRAs or 401(k)s, then you essentially co-own your account(s) with the IRS.

Therefore, we use strategies like Roth conversions and tax location so that if tax rates rise to cover the national debt later, you keep a bigger slice of your own pie.

Here’s what this looks like in practice:

  • Tax-Protected Placement: We keep high-tax investments, like REITs and high-yield bonds, inside your IRAs. This helps shield these higher interest payments from being taxed at your ordinary income rate.
  • Tax-Efficient Growth: We prioritize low-turnover index funds and ETFs in your taxable brokerage accounts. These assets generate very little tax drag, allowing you to keep more of your returns compounding over time. In fact, we’ve shared how compound interest plays a vital role in maintaining your retirement lifestyle.
  • Strategic Municipal Bonds: For clients in higher tax brackets, we use municipal bonds in taxable accounts. This creates a federal tax-free income stream without “wasting” the valuable tax-deferred space inside your retirement accounts.

#3—Staying Flexible With Interest Rates

When the government issues more debt, rates generally climb to attract buyers.

Rather than locking you into long-term bonds that might get “stuck” in yesterday’s rates, we use short-to-intermediate bond ladders. This keeps us nimble so we can capture better yields as they happen.

#4—Building Policy-Proof Income

We can’t predict what will happen with Social Security or future fiscal policy.

That’s why we stress-test your plan against different Social Security scenarios and use dynamic “guardrail” modeling to build diversified income streams.

We want your retirement to stay stable regardless of shifting economic policies.


The Bottom Line

The national debt is an economic reality.

It’s also a factor we weigh carefully when managing your long-term strategy.

If you’d like to sit down and go over the specifics of your portfolio, reach out anytime.

–David Bunker, Financial Advisor & Licensed Fiduciary

P.S. In case you missed it, our latest post explains why Markets Don’t Send Invitations When the Best Days Arrive.


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Filed Under: Economy, Financial Planning, National Debt, Windsor Insights

Mid-Year Review: Small life changes can have big financial impacts

June 20, 2025 by David Bunker

Welcome to summer!

Longer days, warmer weather and a fresh mid-year perspective.

June is the perfect time to take stock of what’s changed in your life, and what might be just around the corner.

Even small life shifts can carry big financial implications, which is why a mid-year review can be so valuable.

What’s changed in your world?

Today’s discussion includes:

  • Reviewing your life changes that may warrant a financial plan update.
  • A checklist to help stretch your retirement income.
  • Tips for backing up and protecting essential documents.

Mid-Year Review: What’s changed?

Life can throw us curveballs and priorities can shift, so let’s make sure your financial plan is still aligned with what you want to achieve.

Give us a call if any of the following applies to you:

Job or Income Changes: A new role, early-retirement offer, added income stream, selling a business? These changes typically affect taxes, benefits (e.g., Medicare IRMAA penalty) and investing strategies. There are, however, financial moves we can often make to offset downside ramifications.

[Related Resource]: Planning Your Final Days of Work Before Retiring

Family Milestones: Marriage, divorce, birth, death, aging parents or adult children with new special needs may require estate or insurance updates.

Health: A recent diagnosis or nearing age 65? Let’s make sure your healthcare plans are in place. Also, if you want to learn more about long-term care insurance, contact us. We’re happy to discuss the pros, cons and costs. Keep in mind, we don’t sell insurance. However, we have long-standing relationships with insurance specialists.

Large Purchases, Sales or Windfalls: Selling a home, funding college or receiving an inheritance? Planning ahead can help reduce financial surprises.

Retirement Approaching: If retirement is just a few years away, it’s time to solidify your plans. A smart Social Security strategy and a well-timed savings withdrawal plan can often extend the life of your retirement funds. We’ll also help you establish a two-to-four-year financial safety net and structure your withdrawals to minimize taxes. For a closer look at our approach, check out: How To Spend Confidently & Without Regret in Retirement.


Prolonging Retirement Income (Checklist)

Whether you’re already retired or planning to be soon, this checklist can help you identify steps that may extend your savings. It’s a great resource to review annually.

[Download the checklist]


Are Your Essential Documents Backed Up and Safe?

If there were a house fire tomorrow, would you have what you need? A simple fire-safe box can help you protect the basics, including:

  • Birth Certificates
  • Digital Account Logins
  • Emergency Contact List
  • Estate Documents
  • Home Inventory Photos/Video (for insurance claims)
  • IDs & Passports
  • Insurance Policies
  • Key Warranties (e.g., new roof, solar panels, windows, etc.)
  • Loan Documents
  • Social Security Cards
  • Spare Emergency Cash
  • Vehicle Titles

Digital Vault

Our clients have access to a secure digital vault.

It’s a private, encrypted space where you can store digital copies of key documents, including those listed above but also scans of: credit cards, divorce decrees, marriage certificates, property records and more. The vault is accessible anytime, from anywhere, securely.


Fire-Safe Boxes for Important Items

To help protect your important documents, look for a fire-safe box with a UL 72 or ETL certification, a 120-minute fire rating and water resistance.

Underwriters Laboratories (UL) and Electrical Testing Laboratories (ETL) are Nationally Recognized Testing Laboratories. They independently test products to stringent safety and performance standards.1

Important: Your protection-rating needs may vary. For example, if you’re looking for a safe that protects digital media or is burglary resistant, these require different UL classes.

American Security has some helpful articles regarding safes, including Why Safe Ratings Matter.2

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Sources:

1: Osha.gov, Current List of NRTLs: https://www.osha.gov/nationally-recognized-testing-laboratory-program/current-list-of-nrtls

2: American Security, Why Safe Ratings Matter: https://americansecuritysafes.com/why-safe-ratings-matter

Filed Under: Financial Planning, Retirement, Windsor Insights

Planning Your Final Days of Work Before Retiring

May 22, 2025 by David Bunker

The Calm After the Work Is Do

Today, we:

  • Discuss eight actions to take before you give retirement notice to your employer.
  • Provide a detailed checklist of essential pre-retirement tasks.

As you start thinking seriously about your final days of work before retirement—whether that’s at age 62, 67 or another time—there are a few key actions that help things go more smoothly.

Now, let’s look at eight actions to take before your last day of work:

#1—Retire to Something, Not Just from Work

Retirement isn’t just about leaving your job.

It’s about building a life you want to live. Whether that means a part-time job, volunteering, spending time with the grandkids or finally joining “that” gym—it’s important to have a purpose.

Beyond what you’ll be “doing” in retirement, it’s equally important to understand how you might feel and how your health could be impacted by this major transition.


Quick Tip by Dave Bunker, Watch the Video Now >


#2—Understand the Emotional Shift and Health Impact

The first year of retirement can bring a surprising health risk: stress-related heart issues spike.

The transition from earning and saving to drawing down what you’ve built is a big emotional adjustment.

Background:

Harvard School of Public Health researchers looked at rates of heart attack and stroke among men and women in the U.S. Health and Retirement Study. Among 5,422 participants, those who had retired were 40% more likely to have had a heart attack or stroke than those who were still working.1

The increase was more pronounced during the first year after retirement, before leveling off. Overall, research on retirement’s health effects is mixed.2


Our Recommendation…

Retirement isn’t a one-time event; rather, it’s a transition.

Many retirees experience changes in identity, routine and social connection. That’s why it’s important to prepare not just financially, but emotionally as well.

To better understand the emotional journey, check out this helpful TED Talk: 4 Phases of Retirement…and the Psychological Challenges.3 The four phases include: Vacation, Feeling Lost, Trial and Error, and Reinvent and Rewire.


#3—Clean Up and Consolidate Your Financial Life

Now is the time to tidy up your financial accounts, including:

  • Review and possibly consolidate old 401(k)s or other workplace plans into an IRA. While some 401(k)s are worth keeping, IRAs usually offer more flexible withdrawal options and simplify things for your heirs.
  • Open any needed accounts before your final day to avoid delays. For instance, give us a call about a month before you retire so we can help you set up the IRA account you’ll use to roll over your 401(k), 403(b) or similar.
  • If you’re receiving a pension, let’s analyze your options (lump sum vs. monthly annuity, single life vs. joint life, etc.) using our Income Lab modeling tool. Keep in mind, most pension decisions need to be made at least 60 days before retirement. Also, if you’re taking a lump sum, put it into an IRA. If you leave it in your brokerage, you’ll pay taxes on ordinary income. 

TIP: If you’re receiving a bonus or cashing out unused vacation time, it may impact your taxes or final 401(k) contributions. Therefore, timing your retirement date matters. Also, hold off rolling over your 401(k) into your IRA until your final contribution, unused vacation time, bonus, etc. hit.


#4—Secure Healthcare Coverage

Are you eligible for Medicare (typically at age 65)? Or will you need COBRA or private insurance? Will you want Medicare Advantage?

While pondering the latter, you’ll also want to revisit your healthcare proxy, powers of attorney and estate documents.

Important: If you’re 63 or older, let’s analyze your income to avoid triggering IRMAA surcharges (Income Related Monthly Adjustment Amount) on Medicare premiums. Being just one dollar over can cost you thousands.

We’ve written more about how this can happen here: Medicare: The $1 Mistake That Costs $3,500.

Free Medicare Counseling Resources:

  • Massachusetts: SHINE (Serving the Health Insurance Needs of Everyone)4
  • New Hampshire: ServiceLink Resource Centers5
  • Fidelity offers complimentary Medicare Planning Services,6 and they host an extensive Medicare learning center.7

#5—Plan Your Retirement Paycheck

We’ll help you set up a retirement income stream that feels like a paycheck.

Resource: Read our detailed blog post about how we help you create your monthly retirement paycheck.8


#6—Watch for Tax Triggers & Withholdings

Be sure to double-check your tax withholding rates for Social Security and pension income. Common options include 7%, 10%, 12%, 22% and higher.

Many retirees forget to set withholdings on these payments, which can lead to surprises at tax time. Alternatively, you can opt to pay quarterly estimated taxes.

As a general rule, use a 20% withholding rate as a starting point. It may need adjusting, but it offers a solid baseline.

Remember, while you’ll no longer pay into Social Security or Medicare, you’ll still owe taxes on retirement income.

Finally, if you’ve had a one-time income event, it’s important we run a tax analysis together.

For Example:

If your total income was $200,000, but $80,000 came from a one-time bonus, we’ll want to explore whether that bonus can be excluded when calculating your Medicare IRMAA.

Lastly, consider if there is anything else you should be doing right now, e.g., taking capital gains.


#7—Decide What Insurance to Keep (and What to Let Go)

As your needs change, it’s smart to review any life or long-term care insurance policies.

Key questions to ask yourself include:

  • Is your life insurance portable?
  • Do you still need it?
  • Should we evaluate or add long-term care coverage?

#8—Finalize Your Budget

A budget is a living, breathing document; it’s never truly final. Still, it’s important to think about how your spending patterns will shift in retirement.

For example, retirement may mean:

  • Less spending on commuting, work clothes or lunches out, but more on travel, healthcare, hobbies or RV maintenance.
  • Mortgage payments disappearing, but insurance or family support costs rising.
  • Savings on payroll taxes, but higher utility bills from being home more.
  • Dropping life insurance premiums, but adding Medicare costs, prescriptions or home repairs.

Resource: Download our handy budgeting worksheet.9

Understanding these trade-offs now helps set realistic expectations and keeps your retirement income plan on track.10


RESOURCE: Retiring Checklist

To help you think through additional retirement considerations, here’s a detailed checklist: What issues should I consider before I retire?11

Within the above checklist are links to other checklists and flowcharts that help answer the following questions:

  • Will I Avoid IRMAA Surcharges on Medicare Part B & Part D?
  • What Issues Should I Consider When Purchasing Long-Term Care Insurance?
  • Should I Consider Doing A Roth Conversion?
  • What Issues Should I Consider When Establishing My Charitable Giving Strategy?
  • What Issues Should I Consider Before I Update My Estate Plan?
  • Am I Eligible for Social Security Benefits If I Have Been Divorced?
  • Am I Eligible For Social Security Benefits As A Surviving Spouse?
  • Can I Make A Deductible Contribution To My HSA?

Next Steps

If you’d like an updated look at your retirement income and tax projections, give us a call. We’re happy to revisit the numbers as often as you need, regardless of how close or far off your retirement may be.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Sources:

1: Harvard Health Blog, Is retirement good for health or bad for it? https://www.health.harvard.edu/blog/is-retirement-good-for-health-or-bad-for-it-201212105625

2: National Library of Medicine, Transition to retirement and risk of cardiovascular disease: Prospective analysis of the US Health and Retirement Study https://pmc.ncbi.nlm.nih.gov/articles/PMC3367095/

3: TED: 4 Phases of Retirement…and the Psychological Challenges, https://www.ted.com/talks/dr_riley_moynes_the_4_phases_of_retirement

4: Mass.gov, Serving the Health Insurance Needs of Everyone (SHINE) Program, https://www.mass.gov/info-details/serving-the-health-insurance-needs-of-everyone-shine-program

5: New Hampshire DHHS, Aging and Disability Resource Centers, https://www.dhhs.nh.gov/programs-services/adult-aging-care/aging-and-disability-resource-centers

6: Fidelity, We are Fidelity Medicare Services, https://medicare.fidelity.com/about-us/

7: Fidelity, Learn about Medicare, https://medicare.fidelity.com/learning-center/

8: Windsor Wealth Management, How To Spend Confidently & Without Regret in Retirement, https://windsorwm.com/how-to-spend-confidently-without-regret-in-retirement/

9: Windsor Wealth Management, Budgeting Worksheet, https://windsorwm.com/wp-content/uploads/2023/10/Budget-Worksheet.xlsx

10: Windsor Wealth Management, 3 Steps to Help Your Money Outlive–You, https://windsorwm.com/3-steps-to-help-your-money-outlive-you/

11: Windsor Wealth Management, What Issues Should I Consider Before I Retire, https://windsorwm.com/wp-content/uploads/2025/05/What-Issues-Should-I-Consider-Before-I-Retire-2025.pdf


Filed Under: Financial Planning, Retirement, Windsor Insights

Home Energy Audits and Energy Tax Credits

April 16, 2025 by David Bunker

Is your home leaking money?

Wealth isn’t just about accumulation; it’s about being intentional with your resources.

Optimizing your home’s energy efficiency is a prime example.

Just as we seek to help maximize your financial returns, you can maximize your home’s comfort and value, while also leveraging energy credits to lower your taxes.


Are your cooling and heating systems energy efficient?

Our goal today, is to help you:

– Discover hidden savings via a professional home energy audit.

– Reduce taxes by leveraging energy credits.

– Understand two key 2025 energy tax credit changes.

– Increase awareness of energy-efficiency scams.


Useful Home Energy Audits

A good energy audit includes a detailed report of where your home is losing energy, and what you can do to fix it.  

The first step, is finding a certified energy auditor. Specifically, a professional who’ll provide you unbiased information and isn’t selling products.


Finding a Reputable Auditor

The U.S. Department of Energy recognizes about 10 home energy auditor qualified certification programs for the Energy Efficient Home Improvement Credit.

To find certified professionals near you, try the Building Performance Institute (BPI) locator. Keep in mind, BPI is just one locator option.

Ideally, select an auditor that doesn’t perform repairs. This helps ensure less bias results.

Related…

Mass Save® is a collaboration of Massachusetts utilities that offer home energy assessments (at no cost), rebates and incentives to help you reduce your energy costs.


Incentive Example:

The Mass Save HEAT Loan offers 0% financing for eligible energy-efficient upgrades. Starting January 1, 2025, you can finance up to $25,000. The financing covers a range of improvements, including insulation, heat pumps, batteries and more.

Most states offer energy-efficiency programs, supported by state, utility and federal incentives, including New Hampshire.

Therefore, before upgrading any cooling or heating system, or replacing any appliance, be sure to check for available rebates and incentives.

Pinpointing where your home loses the most energy will help you prioritize repairs and maximize IRS home energy credits.


Resource: Here’s a helpful chart listing what to expect an auditor to have for tools, (e.g., combustion analyzer, infrared camera, digital probe thermometer, etc.) and what the audit entails.

Finally, watch out for unsolicited “free” energy audit offers. Some companies use these to push you into buying things you don’t need. Always double check who the auditor works for and get a few different opinions before agreeing to any work or signing on the dotted line.


Home Energy Tax Credits & Key 2025 Changes

The Energy Efficient Home Improvement Credit is available for qualifying home improvements made from January 1, 2023 through 2032. To qualify for these credits, generally the improvements must be for your primary residence and use only new materials and systems.

2 Key Changes:

There have been two key changes to the program starting in 2025, including:

#1—Energy-efficient products eligible for the credit need to be manufactured by “qualified” manufacturers.

The IRS is establishing a program to certify manufacturers whose products meet specific energy efficiency standards. This requirement helps ensure the products receiving tax credits are genuinely contributing to energy savings.

#2—When claiming the credit, you must provide the Product Identification Number (PIN) for the qualifying items on your tax return.

Basically, the PIN is a unique ID the IRS uses to ensure the product meets standards, comes from a legit company and matches your credit claim.


Watch Out for Energy-Efficiency Scams

The number of U.S. solar installations is expected to double by 2030, according to the Solar Energy Industries Association®.

Therefore, it’s not surprising we’re seeing increases in solar scams.

The U.S. Treasury describes popular solar scams in their article, Consumer Solar Awareness. (It also talks about buying vs. leasing solar power systems.)

The article highlights several scam tactics, including:

– Sales pitches saying, “This is a government program” to make you think a solar installation is free or government-endorsed.

– Promises of free solar panels and limited-time offers and other pressure tactics urging you to sign up without examining the details.

– Promises of tax credits even though you owe no taxes or promises that the government will send you a tax rebate check in the mail.

Overall, solar panels may be a good option to lower your energy costs, but take your time when evaluating your options.


Buyer Beware: In general, if something is unsolicited, creates a sense of urgency, demands immediate or unusual payment, or sounds too good to be true—assume it’s a scam.

[Related]: Since the weather is getting warmer, watch out for paving scams.


Helpful Tips: No matter if you’re buying a new home or an appliance, be sure to look for the Energy Star mark. Keep in mind, the Energy Star isn’t always the only requirement for tax credits. But, it’s a good indicator of energy efficiency and, therefore, a good place to start.


Finally, don’t forget about Consumer Reports, a nonprofit organization that provides unbiased testing and ratings of products and services, (e.g., new A/C, refrigerator, smart thermostat, etc.). You can often access their reports online for free with most library memberships.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Bay Colony Advisors, DBA Windsor Wealth Management, is not a Certified Public Accountant and does not provide tax, legal, or accounting advice. Any tax-related information provided is for general informational purposes only and should not be construed as legal or tax advice. Each individual’s tax situation is unique, and you should consult with your own tax, financial, or legal advisors before making any decisions. We strongly recommend seeking the advice of a qualified CPA or other professional for personalized tax advice.

Filed Under: Financial Planning, Taxes, Windsor Insights

  • Page 1
  • Page 2
  • Page 3
  • Go to Next Page »

Footer

Amplify Your Retirement Income

"Prolonging Retirement Income" Checklist
Please enable JavaScript in your browser to complete this form.
Name *
Loading

Windsor Insights

Market Update: Good News & Some Caution Signs

[Quick Reminder: Open enrollment is approaching! See our post 5 Financial Tasks to Tackle Before Fall for helpful tips on reviewing your benefits and … [Read More...] about Market Update: Good News & Some Caution Signs

More Posts from this Category

  • Home
  • About
  • Testimonials
  • Contact

Windsor Wealth Management, LLC · 27 Main Street · Topsfield, MA 01983 · (978)887-6940 · WindsorWM.com · Email Us

Investment Advisory Services offered through Bay Colony Advisors, an SEC Registered Investment Advisor

Disclosure
Form ADV Part 2A – Disclosure Brochure
Form ADV Part 3: Relationship Summary Bay Colony Advisory Group, Inc.

Copyright © 2026 · Website Design · Admin

Copy written by financial services writer Sharron Senter