• Skip to main content
  • Skip to footer

Windsor Wealth Management LLC

Investment service in Topsfield, Massachusetts

  • Home
  • About
    • Disclosure
  • Our Difference
  • Services & Fees
    • When to Hire a Financial Advisor
    • FAQ’s
  • Blog
  • Retirement Checklist
  • Contact

Retirement Planning

Should you worry about Social Security?

September 15, 2026 by David Bunker Leave a Comment

It feels like every few months another headline warns that Social Security is running out of money.

In reality, Congress has several options to keep the program funded.

So, let’s look beyond the headlines at what’s actually happening, and what can be done about it.

A Confident Retirement Starts With Understanding Your Options
(Image Source: Gemini AI)

Where the Money Comes From

Before we look at legal levers, let’s clear up how Social Security actually works…

Overall, it’s designed to be self-funding: you and your employer each contribute 6.2% of your wages to Social Security, and benefits are paid from the Social Security Trust Funds. (Social Security has two funds.)1

In the past, there were many more workers than retirees, creating surplus cash that was set aside in the trust funds.

Today, Social Security takes in less than it pays out in benefits, so it’s drawing on its trust fund reserves to make up the difference.

So when people say, “Social Security is becoming insolvent,” what this actually means is that the “extra” savings are getting low, leaving primarily payroll taxes to cover benefits.

Keep in mind, in the 1950s there were roughly 16.5 workers paying into the system for every Social Security beneficiary. Today, there are only about 2.6 workers per beneficiary.2

Also, not everyone pays into the system. Many state employees, teachers and others rely on separate government pensions instead of Social Security.


Fixing the Funding Gap

Congress has several policy levers it can pull before benefits are impacted by a funding shortfall.

These aren’t recommendations, but examples of the options Congress could consider, including:

Raising or Removing the Wage Limit: Right now, Social Security taxes only apply to earnings up to $184,500 (for 2026). Raising or removing this cap would mean Social Security taxes apply to more income, bringing in additional revenue.

Increasing the Payroll Tax: Gradually raising the tax rate by just a fraction of a percentage point across the workforce would create a steady stream of new funding.

Using Other Tax Revenues: Additional funds could come from outside payroll taxes, e.g., corporate taxes or capital gains.

Adjusting the Retirement Age: Pushing the full retirement age (FRA) to 68 or 69 for younger workers gives the program time to adjust, without touching benefits for anyone currently retired.

Rebalancing Benefit Growth: Keep full, promised benefit growth for lower-wage workers while slightly slowing how quickly benefits grow for higher-income brackets.

Modifying Cost-of-Living Adjustments (COLAs): Adjust how annual cost-of-living increases are calculated to reflect how people actually shop when prices increase.

For Example:

Standard inflation calculations using the Consumer Price Index (CPI) assume a retiree keeps buying expensive beef even if prices jump 15%.

An updated formula (Chained CPI) recognizes that people adjust by buying cheaper options, e.g., chicken, which results in a lower inflation rate, enabling slightly smaller annual benefit increases.


Bottom Line

Social Security does face a funding challenge, but “running out of money” doesn’t mean benefits suddenly disappear—despite what some headlines suggest.

Instead, there are many options to bring more money into the system and reduce future costs.

The challenge is deciding which changes to make.

In the meantime, we can plan around what we know and prepare for what may change.

We also address two common Social Security misconceptions here: 2 Social Security Myths Worth a Closer Look.


[Resource]: Social Security is just one piece of the retirement income puzzle. For another perspective on making your retirement savings last, read our post: 3 Steps to Help Your Money Outlive —You


If you have any questions, please reach out.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Sources:

1: SSA.gov, What are the Trust Funds?, https://www.ssa.gov/news/en/press/what-are-the-trust-funds.html

2: SSA.gov, Covered Workers and Beneficiaries, https://www.ssa.gov/oact/TR/2026/lr4b4.html


Filed Under: Financial Planning, Retirement Planning, Windsor Insights Tagged With: Social Security

8 Important Ages in Retirement Planning

August 31, 2026 by David Bunker

It’s hard to believe summer’s almost over.

As the season shifts, it’s important to review your upcoming milestones.

To help you keep track, here’s a quick reference highlighting eight key ages that can trigger important retirement planning opportunities and decisions.


Retirement rules, however, are rarely as simple as reaching a specific age.

Therefore, keep these nuances in mind:

Age 50: Catch-up contributions begin in the calendar year you turn 50. For 2026, the 401(k) catch-up limit is $8,000, increasing to $11,250 for ages 60–63 in 401(k) and other workplace retirement plans.1

[Resource]: See our 2026 Key Financial Data guide for more details regarding contribution limits, Social Security benefits, Medicare premiums, tax rates and more.

Age 59½: The 10% early-withdrawal penalty generally goes away at this age, but that doesn’t make every withdrawal tax-free. For example, Roth IRA earnings are only tax-free once you’re 59½ and have satisfied the 5-year rule from your first Roth contribution.

[Resource]: Read Fidelity’s guide to Roth IRA withdrawal rules for a breakdown of early distributions, penalty exceptions and inherited account requirements.2

Age 62: You can begin Social Security retirement benefits, but claiming before your full retirement age (FRA) permanently reduces your monthly benefit by as much as 30%. Also, if you continue working while receiving benefits before your FRA, the Social Security earnings test may temporarily reduce your benefits.3

Age 65: This is generally when Medicare eligibility begins. However, if you or your spouse are still working and have qualifying employer health coverage, you may be able to delay Medicare enrollment without penalty. Different rules apply depending on your coverage.

Age 67: Once you reach full retirement age, you’re eligible for 100% of your Social Security benefits. Also, the earnings test ends, so extra earned income won’t reduce your benefits.

Age 70: Delaying Social Security beyond your FRA can increase your monthly benefit, but there’s no additional benefit for waiting past age 70.

Age 70½: You can donate tax-free directly from an IRA to a charity via a Qualified Charitable Distribution (QCD).

[Important]: Once Required Minimum Distributions (RMDs) begin, make your QCD before taking your taxable distribution because a QCD can’t retroactively offset a distribution you’ve already taken.

Age 73: Under the SECURE 2.0 Act, the RMD age increased from 72 to 73 starting in 2023. The law also established a second increase, raising the RMD start age to 75 beginning in 2033.

Note: Because RMDs can push you into a higher tax bracket later in life, the years leading up to age 73 create an ideal window to consider tax planning strategies in your 50s and 60s, such as Roth conversions.

Tracking these milestones is important, but turning them into a proactive plan is where the real value lies.

If you have questions, please reach out.

Enjoy the rest of your summer!

Dave

P.S. In case you missed it, we recently published a new blog post: 5 Financial Tasks to Tackle Before Fall


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


Sources:

1: IRS, Retirement Topics-Catch-up Contributions, https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-catch-up-contributions

2: Fidelity.com, Roth IRA withdrawal rules, https://www.fidelity.com/learning-center/trading-investing/roth-ira-withdrawal-rules

3: SSA.gov, What happens if I work and get Social Security retirement benefits?, https://www.ssa.gov/faqs/en/questions/KA-01921.html

Filed Under: Financial Planning, Retirement Planning, Windsor Insights

Longevity Risk: What if you live longer than expected?

July 28, 2026 by David Bunker

When people think about retirement risk, market downturns usually come to mind first.

But there’s another risk that deserves just as much attention: living a long life.

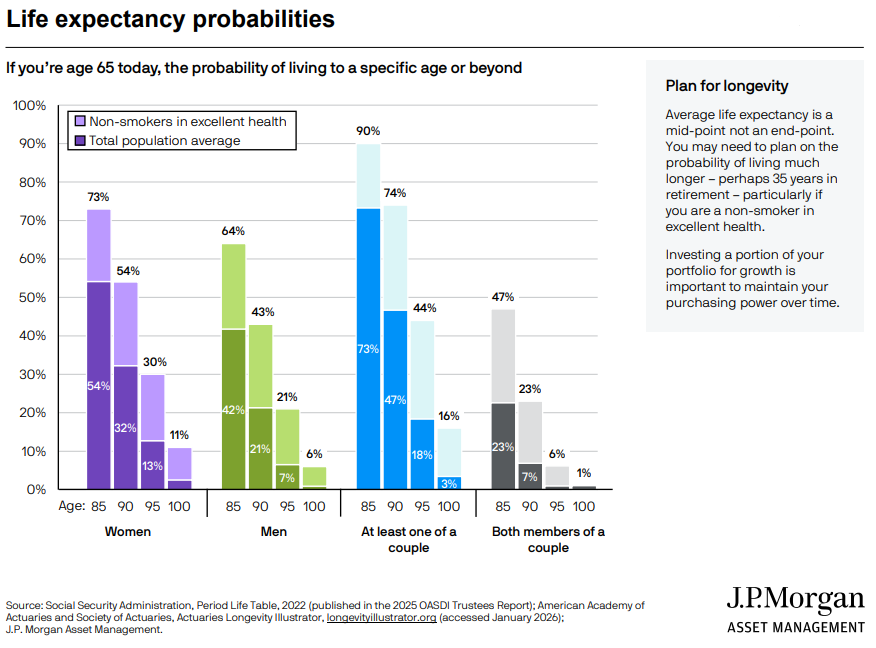
Life expectancy is often thought of in terms of averages (e.g., age 85 for women). But averages can be misleading when you’re planning for retirement.

Consider the chart below.

If you’re 65 today, there’s a 74% chance at least one member of a healthy couple will reach age 90, and a 44% chance one will live to 95.

In reality, the odds of a long retirement are higher than many people realize.


Chart Source: J.P. Morgan Guide to Retirement1

RELATED: We touched upon spouse protection planning in a recent post, and why planning for a surviving spouse becomes increasingly important when retirement may last decades.


Long Retirements

A retirement that lasts 30+ years can place very different demands on your financial portfolio than one lasting 15 or 20 years.

As retirement stretches into decades, carefully managing your investment strategy, withdrawal rate, Social Security timing, taxes, healthcare costs and inflation can help your savings last longer.

Overall, equities play an important role as the long-term growth engine of an investment portfolio, and we believe they help mitigate the longevity risk most people face.


Curious how long you might need your retirement plan to last?

Here are three longevity calculators that provide different perspectives:

Living To 100: A comprehensive questionnaire (40 questions) based on longevity research that considers health, family history and lifestyle.2

Blue Zones® True Vitality Test: Estimates longevity based on the lifestyle habits common among the world’s longest-living populations.3

Social Security Life Expectancy Calculator: A quick government estimate based on your date of birth and gender.4

Of course, no calculator can predict exactly how long you’ll live. However, they can help put longevity risk into perspective.

If you have any questions, please reach out.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Sources:

1) J.P. Morgan Guide to Retirement, https://cdn.jpmorganfunds.com/content/dam/jpm-am-aem/global/en/insights/retirement-insights/guide-to-retirement-us.pdf

2) Living To 100, Scientific Life Expectancy Calculator, https://www.livingto100.com/

3) Blue Zones® True Vitality Test, https://apps.bluezones.com/en/vitality

4) Social Security, Life Expectancy Calculator, https://www.ssa.gov/oact/population/longevity.html


Filed Under: Retirement Planning, Windsor Insights Tagged With: Longevity Risk

Tax Planning During Your 50s & 60s

July 15, 2026 by David Bunker

There are certain moments in life when tax planning becomes especially important. If you’re in your 50s or 60s, this is one of them.

Retirement isn’t simply the end of a career; it’s a transition to a new way of generating income.

While many people spend decades building their retirement savings, fewer spend time planning how to withdraw the assets tax-efficiently.

Image Source: ChatGPT

This is important because:

  • Your tax return may look very different in retirement.
  • Your sources of income begin to change.
  • You may have years when you’re temporarily in a lower tax bracket.

These changes can create valuable financial planning opportunities.

Here are three key retirement tax planning opportunities, followed by a short roundup of other areas to optimize.


#1—Roth Conversions

A Roth conversion allows you to move money from a traditional IRA into a Roth IRA.

You pay income taxes on the amount you convert today, but qualified withdrawals from the Roth IRA are tax-free in the future.

Key benefits include:

  • Creating a source of tax-free retirement income, enabling greater flexibility when managing withdrawals.
  • Filling up a lower tax bracket. (Converting just enough money to maximize today’s low tax rate without pushing yourself into a higher one.)
  • Paying taxes now to reduce taxes later.

[Resource]: For a timeline of critical milestones—including RMD start dates and Social Security thresholds—see our guide: 8 Important Ages in Retirement Planning.

Also, a Roth conversion typically creates a more tax-efficient inheritance for your heirs.

You pay the taxes today, allowing your beneficiaries to receive tax-free withdrawals from an inherited Roth IRA, assuming the Roth rules are met. By comparison, withdrawals from an inherited traditional IRA or 401(k) are generally taxable as ordinary income.1

Roth conversions need to be modeled extensively, since they can increase your modified adjusted gross income. We use two software tools for Roth conversion planning, including Holistiplan and Income Lab.

Reach out if you’d like to model some scenarios.

Keep in mind, Roth conversions can often take years to reach a breakeven point.


#2—Social Security Claiming Timing

Many people think the Social Security decision comes down to one question: Should I claim early or wait?

This is important.

However, the timing of your benefits can also impact your tax strategy.

For Example:

Imagine you retire at age 64 but don’t plan to claim Social Security until age 70.

During these six years, you may have little taxable income because you’ve stopped working, haven’t started receiving Social Security and Required Minimum Distributions (RMDs) haven’t begun.

These lower-income years may create opportunities to:

  • Complete Roth conversions while you’re in a lower tax bracket.
  • Withdraw money from tax-deferred retirement accounts at lower tax rates.
  • Reposition investments before additional retirement income begins.

The key isn’t simply deciding when to claim Social Security. It’s coordinating the decision with the rest of your retirement income plan.


#3—Tax Diversification & Tax–Efficient Withdrawals

A well-diversified portfolio can help manage investment risk, while a tax-diversified portfolio can increase flexibility when it’s time to generate retirement income.

Ideally, your retirement savings are spread across three tax buckets:

  • Taxable (brokerage accounts)
  • Tax-deferred (traditional IRAs and 401(k)s)
  • Tax-free (Roth IRAs and 401(k)s)

Having assets in each of these buckets gives you more choices when generating retirement income. Instead of withdrawing from the same account every year, you can select the accounts that best fit your tax situation.

For Example:

If you realize a large capital gain (e.g., selling an investment property or appreciated investments) you may choose to rely more on tax-free Roth IRA withdrawals for this particular year rather than taking additional taxable distributions from a traditional IRA.

Over time, this flexibility may help make your retirement income strategy more tax efficient.

Related Post: Stress-Free Retirement Spending: The Investment Bucket Strategy

While Roth conversions, Social Security and tax buckets form the foundation of a solid plan, a truly tax-efficient retirement requires watching the fine print, too.


More Opportunities for Lifetime Tax Savings

Finding meaningful savings comes from looking at the whole picture and making small, coordinated moves over time.

Here are nine additional tax-planning opportunities we monitor with you to help minimize your lifetime tax liability:

Medicare IRMAA Surcharges: Manage your income levels to avoid triggering higher Medicare Part B and Part D premiums. Before recognizing a large gain or completing a Roth conversion, look at whether it could push you into a higher IRMAA bracket. Here’s our chart reflecting Medicare Parts B and D income-related adjustments.

Related Post: Medicare: The $1 Mistake that Costs $3,500.

Capital Gains Planning: Review your portfolio for opportunities to strategically harvest tax losses or realize gains to offset future liabilities.

Estate Planning & Lifetime Gifting: Consider whether it makes sense to transfer assets to children or grandchildren now to complement your broader estate and tax plan.

Stock Options & Concentrated Stock: Develop a multi-year plan for diversifying single-stock positions to manage investment risk and tax challenges.

Health Savings Accounts (HSAs): Continue funding your HSA if eligible, since it’s one of the most tax-efficient ways to save for future healthcare expenses.

Catch-Up Contributions: Maximize available catch-up contributions if you’re age 50 or older, and strategically split them between traditional and Roth accounts when applicable. See our chart for contribution limits.

Charitable Giving: Utilize Qualified Charitable Distributions (QCDs) or donate appreciated securities instead of cash to maximize the tax efficiency of your giving.

Required Minimum Distributions (RMDs): Plan ahead for future mandatory distributions well before they begin to help reduce their impact on your ordinary income.

Spouse Protection Planning: Anticipate the transition from a joint to a single tax return, which can increase tax obligations (widow’s tax) since a survivor no longer has the larger joint deduction. Maximizing Social Security to secure a higher survivor benefit, combined with early Roth conversions to reduce future taxable distributions, can help protect a surviving partner’s income down the road.

RESOURCE: Fidelity has written an excellent article explaining 4 Retirement Tax Surprises, including shifting tax brackets, surcharges, the widow’s penalty and fewer deductions.2

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Sources:

1) IRS.gov, Retirement topics-beneficiary, https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-beneficiary

2) Fidelity.com, 4 retirement tax surprises, https://www.fidelity.com/learning-center/wealth-management-insights/avoid-tax-surprises-in-retirement


Bay Colony Advisors, DBA Windsor Wealth Management, is not a Certified Public Accountant and does not provide tax, legal, or accounting advice. Any tax-related information provided is for general informational purposes only and should not be construed as legal or tax advice. Each individual’s tax situation is unique, and you should consult with your own tax, financial, or legal advisors before making any decisions. We strongly recommend seeking the advice of a qualified CPA or other professional for personalized tax advice.


Filed Under: Financial Planning, Retirement Planning, Taxes, Windsor Insights

Quick Tax Check Before the Year Gets Away

June 29, 2026 by David Bunker

Earlier this month, we looked at how major life events (e.g., death, new job or retirement) impact your financial plan.

But sometimes, the most valuable planning opportunities don’t wait for a major milestone.

Instead, they build up quietly in your day-to-day tax situation.

An unexpected bonus or shifting into a new tax bracket can quietly alter your financial landscape. To help ensure you aren’t leaving money on the table, we built a quick Mid-Year Tax Checkup for you below.

Take 60 seconds to scan the checklist and see which items apply to you:

Click here to view or print a full-size version of the checklist.

If several items apply to you or if you’re unsure how they impact your situation, please reach out.

The second half of the year is a great time to make adjustments.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Bay Colony Advisors, DBA Windsor Wealth Management, is not a Certified Public Accountant and does not provide tax, legal, or accounting advice. Any tax-related information provided is for general informational purposes only and should not be construed as legal or tax advice. Each individual’s tax situation is unique, and you should consult with your own tax, financial, or legal advisors before making any decisions. We strongly recommend seeking the advice of a qualified CPA or other professional for personalized tax advice.


Filed Under: Financial Planning, Income, Retirement Planning, Taxes, Windsor Insights, Windsor Money Minute

Market Highs & Mid-Year Review (5 key items)

June 23, 2026 by David Bunker

It’s hard to believe we’re almost halfway through the year, making it a good time to review your financial situation.

Before we look at what’s changed in your life, let’s talk about what’s happening on Wall Street.

Image source: ChatGPT

The S&P 500 posted gains for the last nine straight weeks.

To put this in perspective, a nine-week winning streak has only happened 10 other times since 1945.

Overall, the index is up roughly 11% year-to-date (27% over the last 12 months).

For context, this follows three consecutive years of growth: 26.3% in 2023, 25.0% in 2024 and 17.9% in 2025.


There are several key reasons for this positive momentum, including:

AI Infrastructure: Companies providing the hardware for AI are delivering strong financial results. For example, Dell Technologies saw its share value increase by about 74% in recent weeks following a surge in demand for AI-optimized servers.

Strong Corporate Earnings: First-quarter earnings exceeded expectations, with 84% of large U.S. companies reporting stronger-than-expected profits. Overall earnings are growing at 13–14%—well above the historical average of 6–8%.

[Related Reading]: 3 Key Portfolio Maneuvers & New Market Highs

Geopolitical Resilience and Lower Oil Prices: While ongoing conflicts in the Middle East have caused volatility, recent optimism surrounding ceasefire discussions has kept oil prices relatively stable (about $91 a barrel). This is a significant drop from the $112 a barrel earlier this spring.

Ironically, this positive data can make some feel uneasy.

After all, when stocks continue climbing, it’s easy to start wondering when the next correction will arrive.

In fact, you may find yourself questioning whether it’s time to take some money off the table.

It’s a natural reaction.

But, this famous quote offers an important reminder:


Now, unless your name is Peter Lynch (even he admitted he couldn’t predict the future) market timing is a losing game.

That’s why we focus on what we can control: monitoring your portfolio, managing risk and executing your long-term plan.

[Related Deep Dive]: For an in-depth look at the economy and markets, checkout Capital Group’s 2026 Outlook. It covers the challenge of high valuations and the debate over whether we’re experiencing an AI bubble.


MID-YEAR REVIEW

Life doesn’t stand still (e.g., jobs change, families grow and retirement gets closer).

Even positive changes can create financial implications that are easier to address when we plan ahead.

Therefore, if any of the following applies to you, reach out as soon as possible:

Employment

Have you or your spouse changed jobs, accepted an early retirement package, started consulting work, or added a new income source?

These changes can affect taxes, benefits, Medicare premiums and retirement planning opportunities.

Family

Has your family dynamic changed due to marriage, divorce, a birth, a death, aging parents or a child who needs additional support?

These events often warrant a review of your estate plan, beneficiaries and insurance coverage.

Health

Has anyone in your family experienced a serious illness? Or are you approaching age 65 and preparing for Medicare?

These are important planning milestones that can impact both your finances and healthcare decisions.

Large Purchases, Sales or Inheritance

Are you buying or selling a home? Paying for college? Planning a major renovation or vacation? Selling a business? Receiving an inheritance?

Planning ahead can help reduce tax surprises and help ensure these decisions fit within your overall financial strategy.

Retirement

If you’re considering retirement within the next few years, don’t wait until your last day of work to start planning. Decisions involving Social Security, healthcare coverage, retirement account withdrawals and tax planning are often easier to optimize before you leave your employer.

[Related Reading]: Planning Your Final Days of Work Before Retiring


Overall, ask yourself two simple questions:

#1—Has anything changed in my life?

#2—Am I planning a major event or expense in the next few years?

Remember, small changes today can have a meaningful long-term impact.

If something has changed, or you’re simply wondering whether it matters, please reach out.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Filed Under: Economy, Financial Planning, Investments, Retirement Planning, Windsor Insights

Instead of Retiring, Many Are Doing This (4 Alternatives)

May 27, 2026 by David Bunker

Retirement is changing.

For years, the traditional idea was simple: pick a date, stop working, and move fully into retirement.

But today, many people are taking a different path.

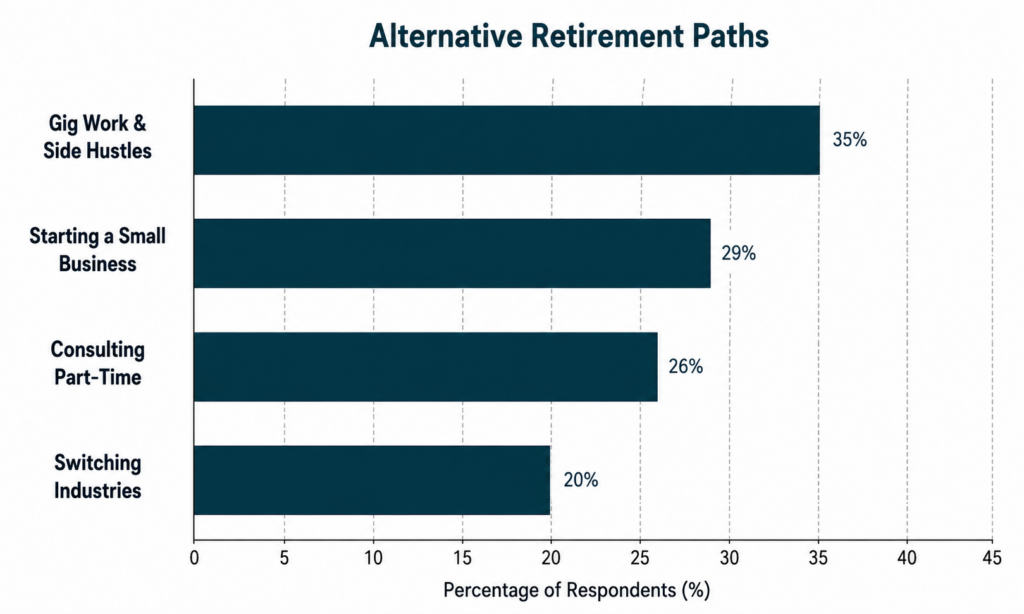
According to a recent Fidelity study, 61% of respondents are moving away from the “hard stop” approach and instead transitioning into retirement gradually.1

While many choose to simply scale back hours at their current jobs, this chart highlights four other ways people are approaching retirement:


Chart Data Source: Fidelity


Among all study respondents, the top retirement transitioning alternatives include gig work and side hustles (35%), starting a small business (29%), consulting part-time (26%), or switching industries altogether (20%).


Retirement Isn’t Just a Date on the Calendar

For many people, retirement is becoming more of a transition than a single decision. This often requires thoughtful planning across both personal and financial areas, including:

  • Defining Your Purpose: Determine exactly how much daily structure, flexibility, intellectual stimulation, optional income and engagement you need.
  • Optimizing Income & Flexibility: Even modest part-time income can reduce portfolio withdrawals while creating more flexibility around taxes and portfolio growth.
  • Controlling Portfolio Withdrawal Timing: An adaptable transition can help protect your portfolio from sequence-of-returns risk, minimizing the need to sell assets during market downturns.
  • Reducing Anxiety: A phased transition allows you to ease into retirement gradually instead of feeling pressured into a sudden life change.

Overall, retirement is a series of choices, not a single decision.

We explore how to navigate this process and what the “4 Phases of Retirement” look like in our post: How to Make the Decision to Retire

Keep in mind, there’s no “right” way to retire.

However, if it’s top-of-mind for you, reach out as soon as possible. The earlier we plan, the more financial flexibility you’ll likely have.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Source:

1) Fidelity Investments® Study, https://newsroom.fidelity.com/pressreleases/fidelity-investments–study–72–of-americans-say-they-will-retire-on-their-own-terms-as-they-embrac/s/609fbcb7-3ea5-4773-a300-0659da881d2a


Filed Under: Financial Planning, Retirement Planning, Windsor Insights

Markets Don’t Send Invitations When the Best Days Arrive

March 27, 2026 by David Bunker

One of the most valuable things you can have during uncertain markets is perspective.

Yet when headlines intensify, it’s only human to consider moving to cash until things settle down. This feeling is often magnified if you’re approaching retirement or have recently transitioned into it.

The challenge?

Markets don’t send invitations when the best days arrive.

In fact, some of the biggest gains usually happen right when things feel the most uncertain.

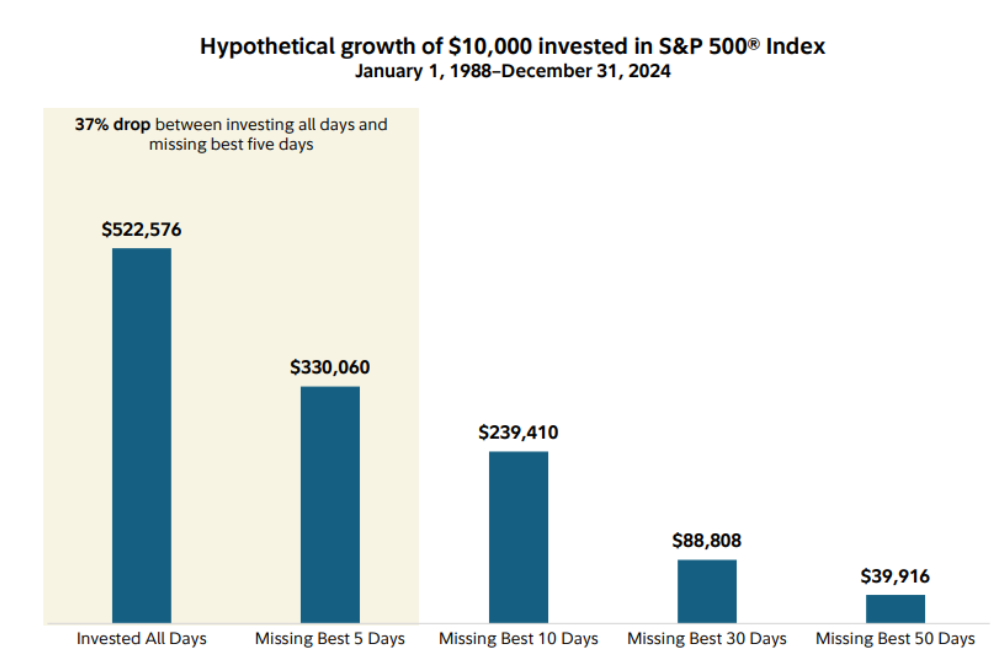
Fidelity shared a chart that illustrates this clearly:

Imagine a $10,000 investment in the S&P 500 back in 1988. That initial amount surpasses $522,000 by 2024, provided you never walked away.

However, missing just the five best market days over that same 37-year period slashes the ending value by roughly 37%.


Find the chart sources and specifications at Fidelity.com1


These few great days are nearly impossible to predict.

What’s more, they often occur shortly after a decline.


Key Goal

Ultimately, our goal is to help you have the resources to live your best retirement life, exactly how you’ve pictured it. Sticking to a disciplined, long-term strategy instead of reacting to headlines is a key component.

For more context behind these numbers, Fidelity breaks it down in this article: 6 reasons why you should consider investing right now.

Reach out with any questions.

–David Bunker, Financial Advisor & Licensed Fiduciary

P.S. In case you missed it, I recently shared my perspectives on the Middle East conflict and what it could mean for your portfolio. Read the post.


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Source:

1. Fidelity.com, 6 reasons why you should consider investing right now, https://www.fidelity.com/learning-center/wealth-management-insights/reasons-to-invest-now


Filed Under: Financial Planning, Investing Philosophy, Investments, Retirement Planning, Windsor Insights

  • Page 1
  • Page 2
  • Go to Next Page »

Footer

Amplify Your Retirement Income

"Prolonging Retirement Income" Checklist
Please enable JavaScript in your browser to complete this form.
Name *
Loading

Windsor Insights

2 Social Security Myths Worth a Closer Look

Earlier this month, we talked about Social Security’s funding challenge and what Congress can do about it. Today, let’s talk about some … [Read More...] about 2 Social Security Myths Worth a Closer Look

More Posts from this Category

  • Home
  • About
  • Testimonials
  • Contact

Windsor Wealth Management, LLC · 27 Main Street · Topsfield, MA 01983 · (978)887-6940 · WindsorWM.com · Email Us

Investment Advisory Services offered through Bay Colony Advisors, an SEC Registered Investment Advisor

Disclosure
Form ADV Part 2A – Disclosure Brochure
Form ADV Part 3: Relationship Summary Bay Colony Advisory Group, Inc.

Copyright © 2026 · Website Design · Admin

Copy written by financial services writer Sharron Senter