• Skip to main content
  • Skip to footer

Windsor Wealth Management LLC

Investment service in Topsfield, Massachusetts

  • Home
  • About
    • Disclosure
  • Our Difference
  • Services & Fees
    • When to Hire a Financial Advisor
    • FAQ’s
  • Blog
  • Retirement Checklist
  • Contact

Financial Planning

8 Important Ages in Retirement Planning

August 31, 2026 by David Bunker Leave a Comment

It’s hard to believe summer’s almost over.

As the season shifts, it’s important to review your upcoming milestones.

To help you keep track, here’s a quick reference highlighting eight key ages that can trigger important retirement planning opportunities and decisions.


Retirement rules, however, are rarely as simple as reaching a specific age.

Therefore, keep these nuances in mind:

Age 50: Catch-up contributions begin in the calendar year you turn 50. For 2026, the 401(k) catch-up limit is $8,000, increasing to $11,250 for ages 60–63 in 401(k) and other workplace retirement plans.1

[Resource]: See our 2026 Key Financial Data guide for more details regarding contribution limits, Social Security benefits, Medicare premiums, tax rates and more.

Age 59½: The 10% early-withdrawal penalty generally goes away at this age, but that doesn’t make every withdrawal tax-free. For example, Roth IRA earnings are only tax-free once you’re 59½ and have satisfied the 5-year rule from your first Roth contribution.

[Resource]: Read Fidelity’s guide to Roth IRA withdrawal rules for a breakdown of early distributions, penalty exceptions and inherited account requirements.2

Age 62: You can begin Social Security retirement benefits, but claiming before your full retirement age (FRA) permanently reduces your monthly benefit by as much as 30%. Also, if you continue working while receiving benefits before your FRA, the Social Security earnings test may temporarily reduce your benefits.3

Age 65: This is generally when Medicare eligibility begins. However, if you or your spouse are still working and have qualifying employer health coverage, you may be able to delay Medicare enrollment without penalty. Different rules apply depending on your coverage.

Age 67: Once you reach full retirement age, you’re eligible for 100% of your Social Security benefits. Also, the earnings test ends, so extra earned income won’t reduce your benefits.

Age 70: Delaying Social Security beyond your FRA can increase your monthly benefit, but there’s no additional benefit for waiting past age 70.

Age 70½: You can donate tax-free directly from an IRA to a charity via a Qualified Charitable Distribution (QCD).

[Important]: Once Required Minimum Distributions (RMDs) begin, make your QCD before taking your taxable distribution because a QCD can’t retroactively offset a distribution you’ve already taken.

Age 73: Under the SECURE 2.0 Act, the RMD age increased from 72 to 73 starting in 2023. The law also established a second increase, raising the RMD start age to 75 beginning in 2033.

Tracking these milestones is important, but turning them into a proactive plan is where the real value lies.

If you have questions, please reach out.

Enjoy the rest of your summer!

Dave

P.S. In case you missed it, we recently published a new blog post: 5 Financial Tasks to Tackle Before Fall


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


Sources:

1: IRS, Retirement Topics-Catch-up Contributions, https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-catch-up-contributions

2: Fidelity.com, Roth IRA withdrawal rules, https://www.fidelity.com/learning-center/trading-investing/roth-ira-withdrawal-rules

3: SSA.gov, What happens if I work and get Social Security retirement benefits?, https://www.ssa.gov/faqs/en/questions/KA-01921.html

Filed Under: Financial Planning, Retirement Planning, Windsor Insights

5 Financial Tasks to Tackle Before Fall

August 19, 2026 by David Bunker

As summer winds down, it’s a good time to take a few minutes to review your finances before the busy fall season begins.

Here are five areas worth checking now.

Image Source: ChatGPT

#1—Plan for Age 18

If your child or grandchild is turning 18 or heading off to college, make sure they have the legal documents that allow you to help them if there’s a medical emergency.

Overall, it’s a good idea to have:

  • HIPAA Authorization
  • Medical Power of Attorney
  • Living Will
  • Durable Power of Attorney

Related Post: Turning Age 18 Legalities & Grandchild College Planning

Also, if your student is living on or off campus, consider whether renter’s insurance makes sense. Replacing specialized computer equipment can be costly. The same goes for e-bikes, which many students use to get around campus and can cost thousands to replace.

Note: While your homeowners policy may cover some losses in a dorm, e-bikes and high-value tech often require special endorsements or separate policies.

Finally, if you’re using a 529 plan, coordinate your withdrawals carefully. Using the same education expenses for both a 529 withdrawal and an education tax credit can lead to unexpected tax consequences.

Fidelity does a nice job explaining it here: How to spend from a 529 college plan1


#2—Get Ready for Open Enrollment (Medicare & Employer)

Open enrollment season is just around the corner.

Medicare’s Annual Enrollment Period runs from October 15—December 7, and many employers hold open enrollment in the fall.

Before finalizing your benefits, consider the following:

Health Insurance Coverage: Compare plan costs, deductibles, provider networks and out-of-pocket maximums to determine whether your current plan is still the best fit.

Prescription Drug Coverage: Make sure your medications are still covered and compare costs if your prescriptions or health needs have changed.

Health Savings Account (HSA) Contributions: If you’re eligible for an HSA, review your contribution amount during open enrollment. HSAs offer triple tax advantages, including tax-deductible contributions, tax-deferred growth and tax-free withdrawals for qualified medical expenses.

Flexible Spending Accounts (FSAs): Estimate next year’s eligible healthcare or dependent care expenses so you can elect an appropriate contribution amount.

Life and Disability Insurance: Review your coverage after major life events (e.g., birth, divorce or marriage). If your employer allows you to increase coverage without a medical exam during open enrollment, consider whether additional protection makes sense before your health changes.

Retirement Plan Contributions: Increase your contribution rate if you’re receiving a raise or bonus. Also, make sure you’re contributing enough to receive your full employer match.

Are you turning age 65 soon?

Your Medicare initial enrollment timeline is different from the annual enrollment period.

Most people can enroll in Medicare beginning three months before the month you turn 65 and continuing for three months afterward.

However, if you’re still covered by an employer health plan, different rules may apply.

Give us a call before you enroll, so we can help you sort through your options.

RESOURCE: Here’s our detailed Medicare guide describing initial enrollment timelines, premiums and deductibles for 2026.


#3—Review Your Taxes and Retirement Savings

Now is a great time to see whether you’re on track.

Review your paycheck withholdings to help avoid an unexpected tax bill or an unnecessarily large refund next spring. Also, check your retirement plan contributions to see if you’re on pace to maximize your 401(k), 403(b), etc. before year-end.

Keep in mind, if you’re age 50 or older and make catch-up contributions, be aware that recent law changes may require higher earners to make catch-up contributions on a Roth (after-tax) basis.


#4—Update Your Homeowners Insurance

Have you remodeled your kitchen, finished a basement or added a garage?

Major home improvements can increase the cost to rebuild your home. If you’ve completed significant renovations, review your homeowners insurance to help ensure your coverage keeps pace with your home’s current value.

Also, if you’ve added a pool, consider adding an umbrella policy.


#5—Plan Ahead for Holiday Spending

It may feel early, but the holiday shopping season will be here before you know it.

Therefore, take a few minutes now to decide how much you want to spend on gifts, travel and entertaining.

Setting a budget early can help reduce financial stress and prevent overspending later in the year.


If you have any questions, please reach out.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.

Source:

1) Fidelity.com, How to spend from a 529 college plan, https://www.fidelity.com/learning-center/personal-finance/college-planning/college-529-spending

Filed Under: College Planning, Estate Planning, Financial Planning, Financial Planning, Taxes, Windsor Insights

Tax Planning During Your 50s & 60s

July 15, 2026 by David Bunker

There are certain moments in life when tax planning becomes especially important. If you’re in your 50s or 60s, this is one of them.

Retirement isn’t simply the end of a career; it’s a transition to a new way of generating income.

While many people spend decades building their retirement savings, fewer spend time planning how to withdraw the assets tax-efficiently.

Image Source: ChatGPT

This is important because:

  • Your tax return may look very different in retirement.
  • Your sources of income begin to change.
  • You may have years when you’re temporarily in a lower tax bracket.

These changes can create valuable financial planning opportunities.

Here are three key retirement tax planning opportunities, followed by a short roundup of other areas to optimize.


#1—Roth Conversions

A Roth conversion allows you to move money from a traditional IRA into a Roth IRA.

You pay income taxes on the amount you convert today, but qualified withdrawals from the Roth IRA are tax-free in the future.

Key benefits include:

  • Creating a source of tax-free retirement income, enabling greater flexibility when managing withdrawals.
  • Filling up a lower tax bracket. (Converting just enough money to maximize today’s low tax rate without pushing yourself into a higher one.)
  • Paying taxes now to reduce taxes later.

Also, a Roth conversion typically creates a more tax-efficient inheritance for your heirs.

You pay the taxes today, allowing your beneficiaries to receive tax-free withdrawals from an inherited Roth IRA, assuming the Roth rules are met. By comparison, withdrawals from an inherited traditional IRA or 401(k) are generally taxable as ordinary income.1

Roth conversions need to be modeled extensively, since they can increase your modified adjusted gross income. We use two software tools for Roth conversion planning, including Holistiplan and Income Lab.

Reach out if you’d like to model some scenarios.

Keep in mind, Roth conversions can often take years to reach a breakeven point.


#2—Social Security Claiming Timing

Many people think the Social Security decision comes down to one question: Should I claim early or wait?

This is important.

However, the timing of your benefits can also impact your tax strategy.

For Example:

Imagine you retire at age 64 but don’t plan to claim Social Security until age 70.

During these six years, you may have little taxable income because you’ve stopped working, haven’t started receiving Social Security and Required Minimum Distributions (RMDs) haven’t begun.

These lower-income years may create opportunities to:

  • Complete Roth conversions while you’re in a lower tax bracket.
  • Withdraw money from tax-deferred retirement accounts at lower tax rates.
  • Reposition investments before additional retirement income begins.

The key isn’t simply deciding when to claim Social Security. It’s coordinating the decision with the rest of your retirement income plan.


#3—Tax Diversification & Tax–Efficient Withdrawals

A well-diversified portfolio can help manage investment risk, while a tax-diversified portfolio can increase flexibility when it’s time to generate retirement income.

Ideally, your retirement savings are spread across three tax buckets:

  • Taxable (brokerage accounts)
  • Tax-deferred (traditional IRAs and 401(k)s)
  • Tax-free (Roth IRAs and 401(k)s)

Having assets in each of these buckets gives you more choices when generating retirement income. Instead of withdrawing from the same account every year, you can select the accounts that best fit your tax situation.

For Example:

If you realize a large capital gain (e.g., selling an investment property or appreciated investments) you may choose to rely more on tax-free Roth IRA withdrawals for this particular year rather than taking additional taxable distributions from a traditional IRA.

Over time, this flexibility may help make your retirement income strategy more tax efficient.

Related Post: Stress-Free Retirement Spending: The Investment Bucket Strategy

While Roth conversions, Social Security and tax buckets form the foundation of a solid plan, a truly tax-efficient retirement requires watching the fine print, too.


More Opportunities for Lifetime Tax Savings

Finding meaningful savings comes from looking at the whole picture and making small, coordinated moves over time.

Here are nine additional tax-planning opportunities we monitor with you to help minimize your lifetime tax liability:

Medicare IRMAA Surcharges: Manage your income levels to avoid triggering higher Medicare Part B and Part D premiums. Before recognizing a large gain or completing a Roth conversion, look at whether it could push you into a higher IRMAA bracket. Here’s our chart reflecting Medicare Parts B and D income-related adjustments.

Related Post: Medicare: The $1 Mistake that Costs $3,500.

Capital Gains Planning: Review your portfolio for opportunities to strategically harvest tax losses or realize gains to offset future liabilities.

Estate Planning & Lifetime Gifting: Consider whether it makes sense to transfer assets to children or grandchildren now to complement your broader estate and tax plan.

Stock Options & Concentrated Stock: Develop a multi-year plan for diversifying single-stock positions to manage investment risk and tax challenges.

Health Savings Accounts (HSAs): Continue funding your HSA if eligible, since it’s one of the most tax-efficient ways to save for future healthcare expenses.

Catch-Up Contributions: Maximize available catch-up contributions if you’re age 50 or older, and strategically split them between traditional and Roth accounts when applicable. See our chart for contribution limits.

Charitable Giving: Utilize Qualified Charitable Distributions (QCDs) or donate appreciated securities instead of cash to maximize the tax efficiency of your giving.

Required Minimum Distributions (RMDs): Plan ahead for future mandatory distributions well before they begin to help reduce their impact on your ordinary income.

Spouse Protection Planning: Anticipate the transition from a joint to a single tax return, which can increase tax obligations (widow’s tax) since a survivor no longer has the larger joint deduction. Maximizing Social Security to secure a higher survivor benefit, combined with early Roth conversions to reduce future taxable distributions, can help protect a surviving partner’s income down the road.

RESOURCE: Fidelity has written an excellent article explaining 4 Retirement Tax Surprises, including shifting tax brackets, surcharges, the widow’s penalty and fewer deductions.2

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Sources:

1) IRS.gov, Retirement topics-beneficiary, https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-beneficiary

2) Fidelity.com, 4 retirement tax surprises, https://www.fidelity.com/learning-center/wealth-management-insights/avoid-tax-surprises-in-retirement


Bay Colony Advisors, DBA Windsor Wealth Management, is not a Certified Public Accountant and does not provide tax, legal, or accounting advice. Any tax-related information provided is for general informational purposes only and should not be construed as legal or tax advice. Each individual’s tax situation is unique, and you should consult with your own tax, financial, or legal advisors before making any decisions. We strongly recommend seeking the advice of a qualified CPA or other professional for personalized tax advice.


Filed Under: Financial Planning, Retirement Planning, Taxes, Windsor Insights

Quick Tax Check Before the Year Gets Away

June 29, 2026 by David Bunker

Earlier this month, we looked at how major life events (e.g., death, new job or retirement) impact your financial plan.

But sometimes, the most valuable planning opportunities don’t wait for a major milestone.

Instead, they build up quietly in your day-to-day tax situation.

An unexpected bonus or shifting into a new tax bracket can quietly alter your financial landscape. To help ensure you aren’t leaving money on the table, we built a quick Mid-Year Tax Checkup for you below.

Take 60 seconds to scan the checklist and see which items apply to you:

Click here to view or print a full-size version of the checklist.

If several items apply to you or if you’re unsure how they impact your situation, please reach out.

The second half of the year is a great time to make adjustments.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Bay Colony Advisors, DBA Windsor Wealth Management, is not a Certified Public Accountant and does not provide tax, legal, or accounting advice. Any tax-related information provided is for general informational purposes only and should not be construed as legal or tax advice. Each individual’s tax situation is unique, and you should consult with your own tax, financial, or legal advisors before making any decisions. We strongly recommend seeking the advice of a qualified CPA or other professional for personalized tax advice.


Filed Under: Financial Planning, Income, Retirement Planning, Taxes, Windsor Insights, Windsor Money Minute

Market Highs & Mid-Year Review (5 key items)

June 23, 2026 by David Bunker

It’s hard to believe we’re almost halfway through the year, making it a good time to review your financial situation.

Before we look at what’s changed in your life, let’s talk about what’s happening on Wall Street.

Image source: ChatGPT

The S&P 500 posted gains for the last nine straight weeks.

To put this in perspective, a nine-week winning streak has only happened 10 other times since 1945.

Overall, the index is up roughly 11% year-to-date (27% over the last 12 months).

For context, this follows three consecutive years of growth: 26.3% in 2023, 25.0% in 2024 and 17.9% in 2025.


There are several key reasons for this positive momentum, including:

AI Infrastructure: Companies providing the hardware for AI are delivering strong financial results. For example, Dell Technologies saw its share value increase by about 74% in recent weeks following a surge in demand for AI-optimized servers.

Strong Corporate Earnings: First-quarter earnings exceeded expectations, with 84% of large U.S. companies reporting stronger-than-expected profits. Overall earnings are growing at 13–14%—well above the historical average of 6–8%.

[Related Reading]: 3 Key Portfolio Maneuvers & New Market Highs

Geopolitical Resilience and Lower Oil Prices: While ongoing conflicts in the Middle East have caused volatility, recent optimism surrounding ceasefire discussions has kept oil prices relatively stable (about $91 a barrel). This is a significant drop from the $112 a barrel earlier this spring.

Ironically, this positive data can make some feel uneasy.

After all, when stocks continue climbing, it’s easy to start wondering when the next correction will arrive.

In fact, you may find yourself questioning whether it’s time to take some money off the table.

It’s a natural reaction.

But, this famous quote offers an important reminder:


Now, unless your name is Peter Lynch (even he admitted he couldn’t predict the future) market timing is a losing game.

That’s why we focus on what we can control: monitoring your portfolio, managing risk and executing your long-term plan.

[Related Deep Dive]: For an in-depth look at the economy and markets, checkout Capital Group’s 2026 Outlook. It covers the challenge of high valuations and the debate over whether we’re experiencing an AI bubble.


MID-YEAR REVIEW

Life doesn’t stand still (e.g., jobs change, families grow and retirement gets closer).

Even positive changes can create financial implications that are easier to address when we plan ahead.

Therefore, if any of the following applies to you, reach out as soon as possible:

Employment

Have you or your spouse changed jobs, accepted an early retirement package, started consulting work, or added a new income source?

These changes can affect taxes, benefits, Medicare premiums and retirement planning opportunities.

Family

Has your family dynamic changed due to marriage, divorce, a birth, a death, aging parents or a child who needs additional support?

These events often warrant a review of your estate plan, beneficiaries and insurance coverage.

Health

Has anyone in your family experienced a serious illness? Or are you approaching age 65 and preparing for Medicare?

These are important planning milestones that can impact both your finances and healthcare decisions.

Large Purchases, Sales or Inheritance

Are you buying or selling a home? Paying for college? Planning a major renovation or vacation? Selling a business? Receiving an inheritance?

Planning ahead can help reduce tax surprises and help ensure these decisions fit within your overall financial strategy.

Retirement

If you’re considering retirement within the next few years, don’t wait until your last day of work to start planning. Decisions involving Social Security, healthcare coverage, retirement account withdrawals and tax planning are often easier to optimize before you leave your employer.

[Related Reading]: Planning Your Final Days of Work Before Retiring


Overall, ask yourself two simple questions:

#1—Has anything changed in my life?

#2—Am I planning a major event or expense in the next few years?

Remember, small changes today can have a meaningful long-term impact.

If something has changed, or you’re simply wondering whether it matters, please reach out.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Filed Under: Economy, Financial Planning, Investments, Retirement Planning, Windsor Insights

Markets Don’t Send Invitations When the Best Days Arrive

March 27, 2026 by David Bunker

One of the most valuable things you can have during uncertain markets is perspective.

Yet when headlines intensify, it’s only human to consider moving to cash until things settle down. This feeling is often magnified if you’re approaching retirement or have recently transitioned into it.

The challenge?

Markets don’t send invitations when the best days arrive.

In fact, some of the biggest gains usually happen right when things feel the most uncertain.

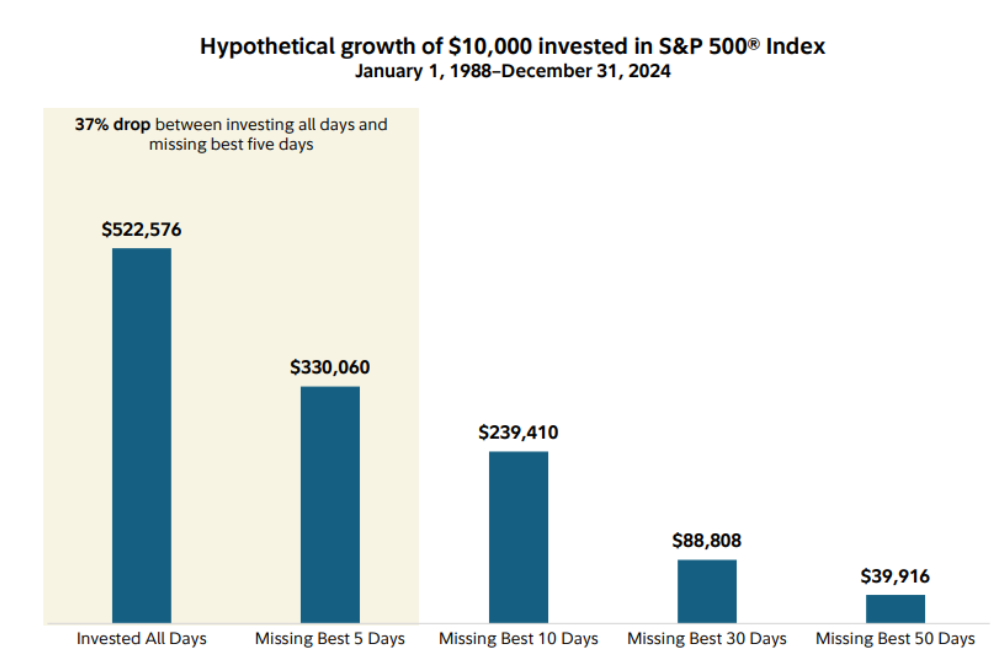
Fidelity shared a chart that illustrates this clearly:

Imagine a $10,000 investment in the S&P 500 back in 1988. That initial amount surpasses $522,000 by 2024, provided you never walked away.

However, missing just the five best market days over that same 37-year period slashes the ending value by roughly 37%.


Find the chart sources and specifications at Fidelity.com1


These few great days are nearly impossible to predict.

What’s more, they often occur shortly after a decline.


Key Goal

Ultimately, our goal is to help you have the resources to live your best retirement life, exactly how you’ve pictured it. Sticking to a disciplined, long-term strategy instead of reacting to headlines is a key component.

For more context behind these numbers, Fidelity breaks it down in this article: 6 reasons why you should consider investing right now.

Reach out with any questions.

–David Bunker, Financial Advisor & Licensed Fiduciary

P.S. In case you missed it, I recently shared my perspectives on the Middle East conflict and what it could mean for your portfolio. Read the post.


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Source:

1. Fidelity.com, 6 reasons why you should consider investing right now, https://www.fidelity.com/learning-center/wealth-management-insights/reasons-to-invest-now


Filed Under: Financial Planning, Investing Philosophy, Investments, Retirement Planning, Windsor Insights

The 3-Year “Buffer Strategy” for Portfolios

February 24, 2026 by David Bunker

When reviewing retirement projections, it’s easy to focus on average annual returns.

In reality, retirement outcomes are shaped less by averages and more by the timing of these returns—a concept known as sequence of returns risk.


EXAMPLE: How Identical Savings Lead to Different Futures

The chart below shows two couples, each starting retirement with $2.5 million and withdrawing $100,000 per year. Over 25 years, they earn the same average return.

The difference, however, is the order in which these returns occur:

Couple A: Experiences a market downturn in the first years of retirement.

Couple B: Experiences the same downturn much later.


A market downturn hits harder when you’ve just retired.

When withdrawals coincide with losses, you’re forced to sell more assets to generate the same income. This shrinks your portfolio and reduces its ability to recover because you have less capital working for you when the market rebounds.

Conversely, declines occurring later in retirement are often easier to absorb.

At this stage, your portfolio has already done the “heavy lifting,” plus it’s continued to grow, creating a financial buffer that helps your savings survive future market turbulence.

Finally, by the time a later downturn hits, your portfolio doesn’t need to support as many future years of income.

Same average returns. Very different outcomes.


RELATED: In case you missed it, we published a new post: How to Make the Decision to Retire. Market behavior is one of several key factors to consider.


Managing Sequence of Returns Risk

Windsor Wealth Management helps you address this risk by setting aside two to four years of income in a conservative investment account. This “buffer” remains stable while still providing modest growth.

It allows retirement spending to continue uninterrupted during market downturns, giving the rest of your portfolio time to recover.

For Example:

If your annual spending is $90,000, we may earmark $270,000 to cover the first three years of retirement.

This upfront reserve helps protect your lifestyle by reducing the need to sell investments when markets are volatile.

Key Action: It’s critical to plan for the “when” of your retirement to help ensure there’s enough time to set these funds aside. (Ready to retire? Reach out as soon as possible.)

Generally speaking, average returns don’t retire people.

Cash flow timing does.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Filed Under: Financial Planning, Investing Philosophy, Windsor Insights, Windsor Money Minute

How to Make the Decision to Retire

February 6, 2026 by David Bunker

Many people assume retirement is a single decision:

“I’m done. I’m retiring.”

In reality, retirement works best as a process, not a one-time leap.

The desire to retire often starts with a feeling: burnout, a personal milestone (e.g., reaching a specific age, becoming a grandparent, paying off a mortgage) or a realization that time matters more than it used to, especially after losing someone close.

The real question isn’t: Can I afford to retire?

Instead, it’s: How do I want this next chapter to look, and what financial options do I have?

Thoughtful financial planning makes a meaningful difference at this juncture.


Retirement Is a Series of Choices

Some people retire all at once.

Others work a few more years, shift to part-time or gradually step back (e.g., reduce from five days to three or cut back responsibilities while keeping key projects).

Some claim Social Security early. Others delay.

Interestingly, some people can look at the same financial data and make completely different decisions, because confidence, lifestyle and comfort matter just as much as the math.

Overall, approaching retirement as a process allows you to test different paths before committing to one.


Why Timing Matters More Than Most People Realize

Retirement outcomes aren’t shaped by a single decision.

Instead, they’re shaped by when decisions are made and how they interact with one another.

A few examples we routinely see:

Markets: Retiring just before or during a market downturn can put added pressure on your portfolio early, when withdrawals begin and flexibility is lowest. If markets decline in these early years, selling investments at lower values can permanently reduce how long your portfolio lasts, even if markets recover later. This is why Windsor Wealth Management focuses on proactive income planning and portfolio guardrails designed to help reduce this risk.

Taxes: The order and timing of withdrawals (taxable, tax-deferred and tax-free accounts) can quietly increase or reduce lifetime tax exposure.

Healthcare and Medicare Costs: The years before Medicare, Medicare enrollment and ongoing healthcare expenses all affect retirement cash flow.

In some cases, income that seems reasonable on paper can trigger higher Medicare premiums if certain thresholds are crossed, aka Income-Related Monthly Adjustment Amount (IRMAA). We explain this “income cliff effect” in our post: Medicare: The $1 Mistake that Costs $3,500

Social Security Timing: While delaying benefits increases income (roughly 8% per year after full retirement age until age 70), the “right” decision depends on longevity risk, health considerations, caregiving needs, portfolio size and tax strategy.

Looking at these factors in isolation can be misleading.

Seeing them together across multiple scenarios helps clarify what’s realistic, what’s flexible and where risks truly lie. It turns uncertainty into clarity by highlighting which decisions matter most while changes are still possible.


The Emotional Side of Retirement Matters

Retirement isn’t just a financial transition; it’s a deeply personal one.

While you’ve likely focused on the “math” for years, many retirees are surprised by how much they miss the structure of a career. Some even feel a loss of identity.

That’s why it’s helpful to think not only about what you’re retiring from, but what you’re retiring to.

To help visualize this journey, watch Dr. Riley Moynes’ TED Talk.1 He explains four distinct psychological phases you’ll likely experience:

#1—The Vacation Phase: The initial excitement of total freedom.

#2—Feeling Lost: Realizing the “honeymoon” is over and missing your old routine.

#3—Experimentation: Trying new activities to find a new sense of purpose.

#4—Reinvention: Successfully creating a fulfilling new identity.

Ultimately, retirement is less about reaching a final destination and more about having the flexibility to evolve along the way. Part of this evolution involves overcoming one of retirement’s greatest challenges: the loss of social connection.

The Harvard Study of Adult Development (one of the longest-running studies on human happiness) highlights that our relationships are the strongest predictor of health and longevity.2


Income Confidence Is Not a Magic Savings Number

A common misconception is that retirement decisions hinge on reaching a single savings target.

In reality, confidence comes from understanding income; specifically, how much is coming in, where it’s coming from and how long it’s likely to last under different conditions. This is one of our core roles: helping you understand how much you can comfortably spend.

This answer is shaped by three key forces:

  • How long you live.
  • When you claim Social Security.
  • How retirement spending changes over time.

We’ve explored these dynamics in more detail here: 3 Critical Retirement Planning Dynamics


Spending With Purpose and Without Regret

Once income is clearly defined, the challenge for many retirees shifts from Can I afford to retire? to How do I spend confidently?

However, this shift isn’t just financial. Moving from a lifetime of saving to relying on your money for income can be a real psychological adjustment—even when the numbers say you’re ready.

That’s why a well-structured financial plan creates guardrails that help turn income into a reliable “retirement paycheck,” reducing the temptation to question every spending decision or react emotionally to market swings.

For Example:

Rather than wondering when or how much to withdraw, our retired clients typically receive predictable, recurring income deposited directly into their checking account each month.

This usually includes Social Security and other reliable income sources, combined with a coordinated monthly “paycheck” from their portfolio—designed around individual income needs and adjusted as conditions change.

If you’d like to see how confident retirement spending actually works in practice, read our post: 3 Steps To Help Your Money Outlive—You. It features a realistic example of a couple who began retirement with $2 million in savings and—after 30 years of steady spending—actually had $2.6 million remaining (more than what they started with).


Is Retirement on Your Mind?

If you’re starting to think about retirement or questioning whether now is the right time, we’re always happy to talk through your options.

In general, it’s helpful to start retirement conversations as early as 10 years out. Doing so creates more options.

For Example:

  • Adjusting how you save (e.g., shifting from a traditional 401(k) to a Roth 401(k)), allowing more control over when and how taxable income shows up in retirement.
  • Building cash reserves to support early retirement years, so you’re not forced to sell investments during a market downturn.
  • Modifying Social Security timing, by modeling multiple claiming scenarios to see how different choices affect income, taxes and long-term outcomes.
  • Planning for healthcare coverage before Medicare begins, while being mindful of potential IRMAA surcharges.

If your retirement is fast approaching, be sure to read: Planning Your Final Days of Work Before Retiring, which includes a short video with a practical tip on preparing for the transition.

In general, most retirement decisions don’t need to be rushed or permanent. However, a few carry lasting consequences if made too quickly.

Approaching retirement as an ongoing process gives you time to explore options, understand trade-offs and move forward with confidence, knowing your plan can adapt as life evolves.

–David Bunker, Financial Advisor & Licensed Fiduciary


Before You Go

Get help optimizing your retirement income. Download our FREE “Prolonging Retirement Income” checklist.

Also, receive help retiring to the life you want, schedule a complimentary financial planning consultation.


This communication was prepared with financial writer Sharron Senter’s assistance, based on interviews with David Bunker, a financial advisor and licensed fiduciary.


Sources:        

1: 4 Phases of Retirement…and the Psychological Challenges, https://www.ted.com/talks/dr_riley_moynes_the_4_phases_of_retirement

2: Good genes are nice, but joy is better. https://news.harvard.edu/gazette/story/2017/04/over-nearly-80-years-harvard-study-has-been-showing-how-to-live-a-healthy-and-happy-life/


Filed Under: Financial Planning, Income, Retirement Planning, Windsor Insights

  • Page 1
  • Page 2
  • Go to Next Page »

Footer

Amplify Your Retirement Income

"Prolonging Retirement Income" Checklist
Please enable JavaScript in your browser to complete this form.
Name *
Loading

Windsor Insights

8 Important Ages in Retirement Planning

It’s hard to believe summer's almost over. As the season shifts, it’s important to review your upcoming milestones. To help you keep track, … [Read More...] about 8 Important Ages in Retirement Planning

More Posts from this Category

  • Home
  • About
  • Testimonials
  • Contact

Windsor Wealth Management, LLC · 27 Main Street · Topsfield, MA 01983 · (978)887-6940 · WindsorWM.com · Email Us

Investment Advisory Services offered through Bay Colony Advisors, an SEC Registered Investment Advisor

Disclosure
Form ADV Part 2A – Disclosure Brochure
Form ADV Part 3: Relationship Summary Bay Colony Advisory Group, Inc.

Copyright © 2026 · Website Design · Admin

Copy written by financial services writer Sharron Senter